


If your C corporation in Cumming or Alpharetta no longer fits the business you run, the pressure can feel immediate. The tax structure may be dragging on cash flow, the ownership setup may be harder to manage, or you may be looking at a cleaner operating model for the next stage of growth. A c corp conversion to llc can solve part of that problem, but it can also create tax, filing, and operational fallout that catches owners off guard.
The move is rarely just a paperwork update. In practice, it affects how the old corporation ends, how the new LLC starts, and what has to be cleaned up with banks, vendors, licenses, lenders, and tax authorities. For business owners in Forsyth County, Fulton County, and across North Georgia, the question is not whether conversion is possible. It is whether conversion is the right move once the legal, tax, and operational pieces are all on the table.
Why Georgia Business Owners Consider Converting Their Corporation
A Georgia owner usually starts thinking about conversion when the current structure no longer fits how the business runs. A C corporation that once made sense for outside capital, formal governance, or a different growth plan can become harder to justify when the owner wants more flexibility, simpler decision-making, or a different ownership setup. In Cumming, GA and Alpharetta, GA, that comes up often for family businesses, closely held companies, and founders who no longer want to carry corporate formalities that do not add much value.
The tax issue is usually part of that pressure. A corporation can create a second layer of tax on distributed profits, and that changes how owners think about retained earnings versus cash they can use. Conversion does not erase the tax problem, though, because the conversion itself can trigger tax consequences. The Tax Adviser explains that a C corporation converting to an LLC is generally treated as a liquidation followed by a contribution of assets to the new entity, which makes the move a real structural change rather than a simple name change (The Tax Adviser).
Practical rule: if the business owns appreciated assets, carries debt, or has contracts tied to the old entity, the conversion question needs a cleanup plan, not just a filing date.
Owners also weigh succession, ownership changes, and day-to-day simplicity. A spouse, sibling, partner, or next-generation owner may find the corporate structure too rigid for the way the business operates. In some cases, the better move is not conversion at all, but changing ownership terms, distribution practices, or governance instead. That is why a direct comparison with the corporate drawbacks matters before anyone signs a conversion filing, especially if the goal is to avoid solving one problem and creating another.
The operational side deserves the same attention. A conversion can leave behind loose ends if the old entity is not fully cleaned up, and those loose ends can show up later in banking, vendor records, tax notices, or compliance files. Owners who assume the paperwork ends with the state filing often run into the sort of after-the-fact mess described in dormant LLC compliance traps, because the same “we will sort it out later” approach can create avoidable trouble during and after the change.
Understanding the Two Legal Paths for Converting a C Corporation
There are really two roads here, and they do not feel the same in practice. One is a statutory conversion, where the state allows the corporation to convert directly into an LLC through a prescribed filing process. The other is a liquidation and reformation route, where the corporation is wound down, the assets and liabilities are moved, and the new LLC is formed separately. Which path exists depends on state law, and one source notes that statutory conversion is available in 35 states (ZenBusiness).
Direct statutory conversion
A direct conversion is cleaner on paper because the state treats the change as one coordinated transaction. In Delaware, for example, the process uses a Certificate of Conversion and a new formation document rather than a piecemeal transfer of every asset one by one, and neutral filing sources note that Delaware's fees for this type of conversion were at least $293 in 2025, split between a $184 Certificate of Conversion and a $109 Certificate of Incorporation (SeedLegals). That gives you a useful benchmark for one major U.S. jurisdiction, even though Georgia owners still need to follow Georgia's own filing mechanics.
This path works best when the business wants continuity and the state offers the process. It can reduce some of the handoff friction, but it does not eliminate tax analysis or post-filing cleanup. The state filing is only part of the move.
Liquidation and reformation
The other route is more manual. The corporation is treated as ending, the owners shift assets and liabilities to the new LLC, and the old entity is formally dissolved. That route is the practical default in states that do not allow direct conversion, and it is often the more realistic framework even when the direct route exists but the company has complicated assets, contracts, or financing arrangements.
That distinction matters because the legal consequences differ. With a direct statutory conversion, the state may treat the entity change as a simple statutory process. With liquidation and reformation, you are dealing with a broader unwind. In real life, the difference often shows up in contracts, lender notices, asset retitling, and tax filings after the paperwork is accepted.
Direct conversion sounds simpler, but the business still has to survive the handoff. The paper can be neat while the operational cleanup stays messy.
If your company is evaluating a conversion while also thinking about a broader tax strategy, it can help to compare the entity move with the tax planning issues that sometimes point in a different direction. Allied Tax Advisors' discussion of Form 2553 and BIG tax help is useful context because it shows how often entity choice is really a larger tax-structure decision, not a single filing choice.
Georgia Filing Requirements and State Specific Procedures
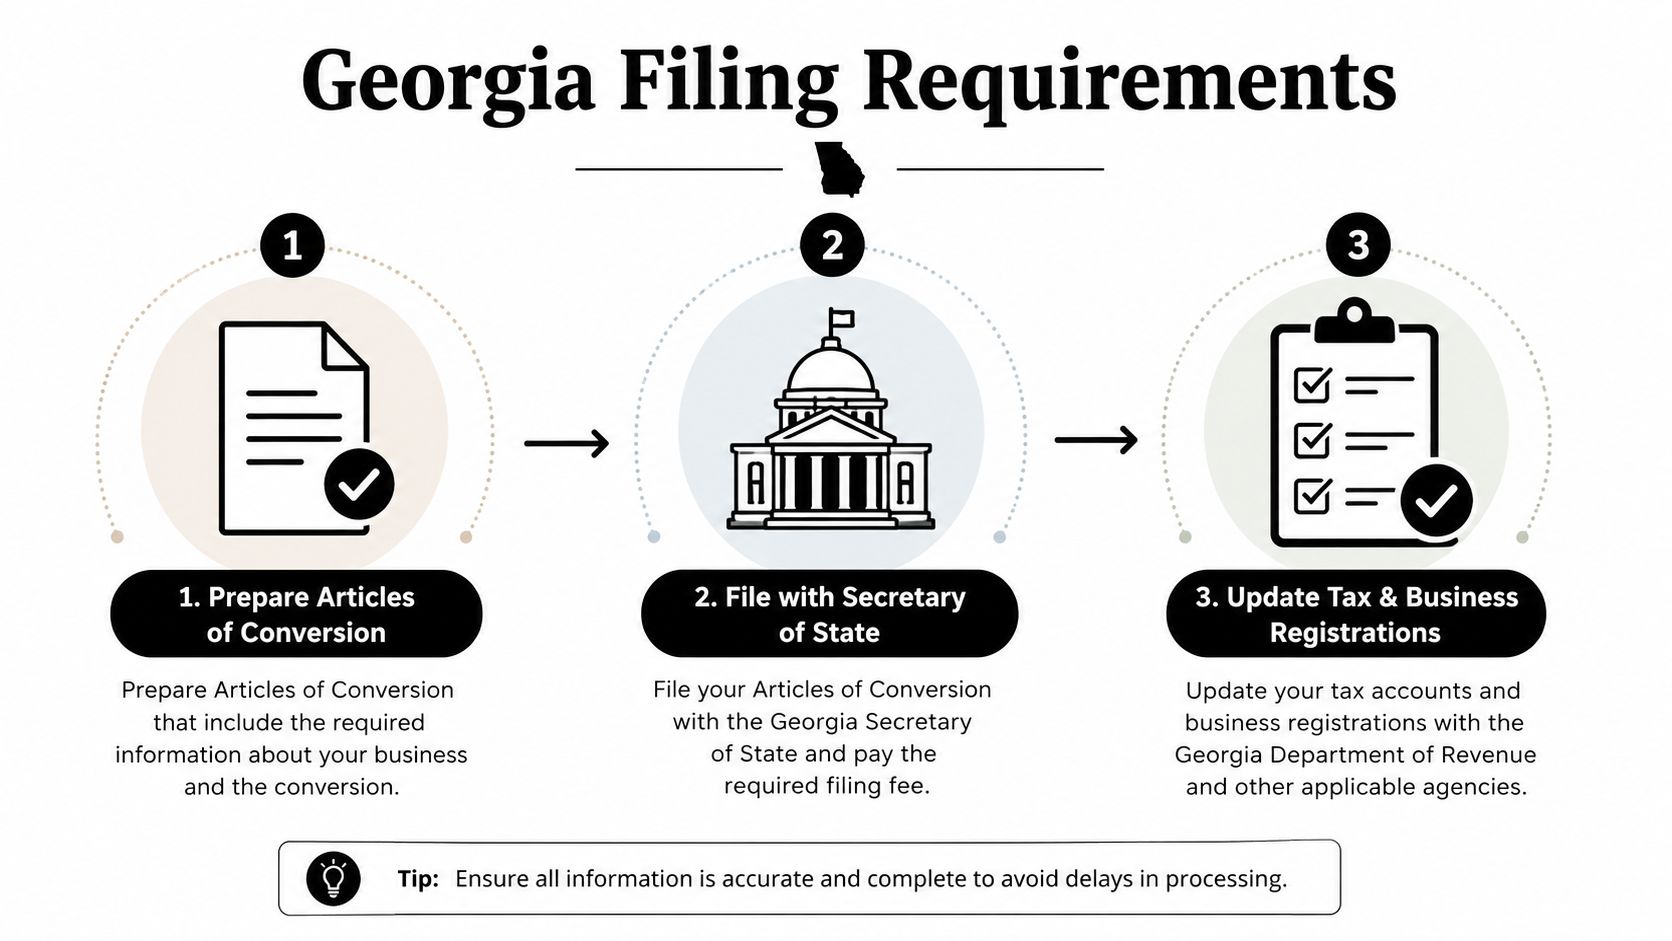
A Georgia conversion starts with the state filings, but the paper trail only works if the rest of the business is lined up behind it. For a c corp conversion to llc, Georgia owners usually have two filing paths. A direct conversion uses the Georgia Secretary of State's conversion process and then updates the LLC's formation records. An indirect route requires winding down the corporation, creating the LLC, and documenting the asset transfer and dissolution in the correct order.
The filing sequence matters because one accepted filing does not clean up the whole transaction. Many owners treat the Secretary of State approval like the finish line, but it only makes the legal change effective on the state side. The company still has to update tax records, bank accounts, licenses, vendor files, and contracts.
What Georgia owners should expect
A practical Georgia conversion file often includes the conversion paperwork, the LLC formation documents, and, if the corporation is being dissolved separately, the dissolution materials for the old entity. Owners in Cumming, Alpharetta, Johns Creek, Milton, Suwanee, Dawsonville, Roswell, Sandy Springs, and Canton usually need time for the non-state pieces as well, since vendors, professional accounts, insurers, and regulators do not update themselves. The state filing is only one step in a larger handoff.
Georgia processing times vary, and the broader business cleanup can extend well beyond the initial filing. The Secretary of State may accept the conversion before the company is ready to operate fully under the new structure, especially if real estate, vehicles, permits, or intellectual property still need to be retitled. That is where the practical work starts, because the legal entity may have changed while the business records still point to the old corporation.
If you want a clean reference point for setting up the new entity side, Miles Hansford's page on LLC creation is a useful starting place for the formation steps that typically follow the state filing. For owners who also need to understand the tax forms tied to the new structure, HireAccountants' LLC tax guide helps explain the reporting side that often gets overlooked during the conversion process.
Georgia filing procedures set the legal framework, but the post-conversion cleanup determines whether the business can function without interruptions.
Federal and State Tax Consequences of Converting Your C Corporation
A C corporation that converts to an LLC is usually treated for federal tax purposes as if the corporation first liquidates, then the owners contribute the assets to the new LLC. That structure can trigger gain at the corporate level on appreciated assets, then a second layer of tax at the shareholder level. In practice, that is why the tax analysis has to happen before the filing, not after it is already done.
Why the tax issue is not a form-filing issue
There is no single IRS form that “converts” a C corporation into an LLC. Practitioners usually focus on entity classification filings such as Form 8832 and the corporation's final Form 1120, but those forms do not erase the tax consequences of the transaction (UpCounsel). The old corporation also files a final Form 1120 and Form 966 to report liquidation-related corporate actions, and the practical point is simple, the business is ending one tax regime and entering another.
That change matters because the post-conversion LLC is often taxed as a partnership or disregarded entity, depending on ownership. The corporation does not disappear from the tax analysis just because the legal structure changes. If the business holds appreciated property, the conversion can create taxable gain at the corporate level before the owners ever begin operating through the LLC.
What business owners often miss
Owners tend to focus on current profits and overlook built-in gain in the corporate balance sheet. If the corporation owns assets that have increased in value, the conversion can surface that appreciation. Debt, basis calculations, and prior distributions can also make the tax result harder to predict than the owner expected. That is why a conversion can become an expensive event even when the filing fee itself looks modest.
Important distinction: an asset transfer, a stock sale, and a conversion are not the same thing for tax purposes, even if the business owner experiences them as one practical change.
State taxes can create another layer of cost. Georgia may treat the move one way for filing purposes while other states where the business owns property, has employees, or holds registrations may require separate reporting or adjustment. Multi-state owners often find that the tax question is tied to the operating footprint, not just the entity conversion itself.
If you are trying to understand how the LLC will file after conversion, a plain-language tax guide such as HireAccountants' LLC tax guide can help frame the reporting side. The core decision is whether conversion makes economic sense at all, because once appreciated corporate assets are part of the transaction, the tax cost can outweigh the structural benefit.
Operational Changes After Your C Corporation Becomes an LLC
The business does not become clean just because the filing is accepted. Banks, vendors, payroll systems, and state agencies still have to be updated, and that is where many owners feel the friction. A conversion that looks finished on paper can stall operations if the cleanup is handled casually.
The checklist that actually matters
- Bank accounts: Re-title or reopen accounts under the LLC name, because deposits and signature authority tied to the old corporation can create confusion.
- Contracts and consents: Review customer agreements, leases, loan documents, and supplier contracts for consent clauses. Some lenders and landlords must approve the entity change before the transfer is valid.
- Licenses and permits: Reissue or update any licenses tied to the corporation name, especially where the regulator ties the permit to the legal entity rather than the trade name.
- Payroll and tax records: Confirm whether the LLC can use the old EIN or needs a new one. Payroll registrations may also need separate updates.
- Assets: Retitle real estate, vehicles, and intellectual property so they sit in the right entity name after conversion.
- Vendor onboarding: Expect W-9 and 1099 updates from vendors, and prepare to provide the LLC's legal and tax details.
These are not optional admin tasks. If they are missed, the old corporation can be left carrying obligations that should have moved, and the LLC can look operationally live while still being legally incomplete.
The biggest practical issue is continuity. Employees need to know which entity is paying them, customers need to know which company is performing the work, and counterparties need clean documentation. A new LLC can inherit the business activity, but it does not automatically inherit every administrative relationship in a way that vendors or lenders will accept without notice.
That is why the post-conversion cleanup should be planned before the filing, not after. If a business operates in North Fulton courts territory, serves clients across Alpharetta and Cumming, or holds multiple licenses, the operational detail can matter as much as the legal structure. Miles Hansford's corporate compliance attorney resource is a useful reminder that the legal work often continues after formation or conversion.
Common Pitfalls and When to Consult a Georgia Business Attorney
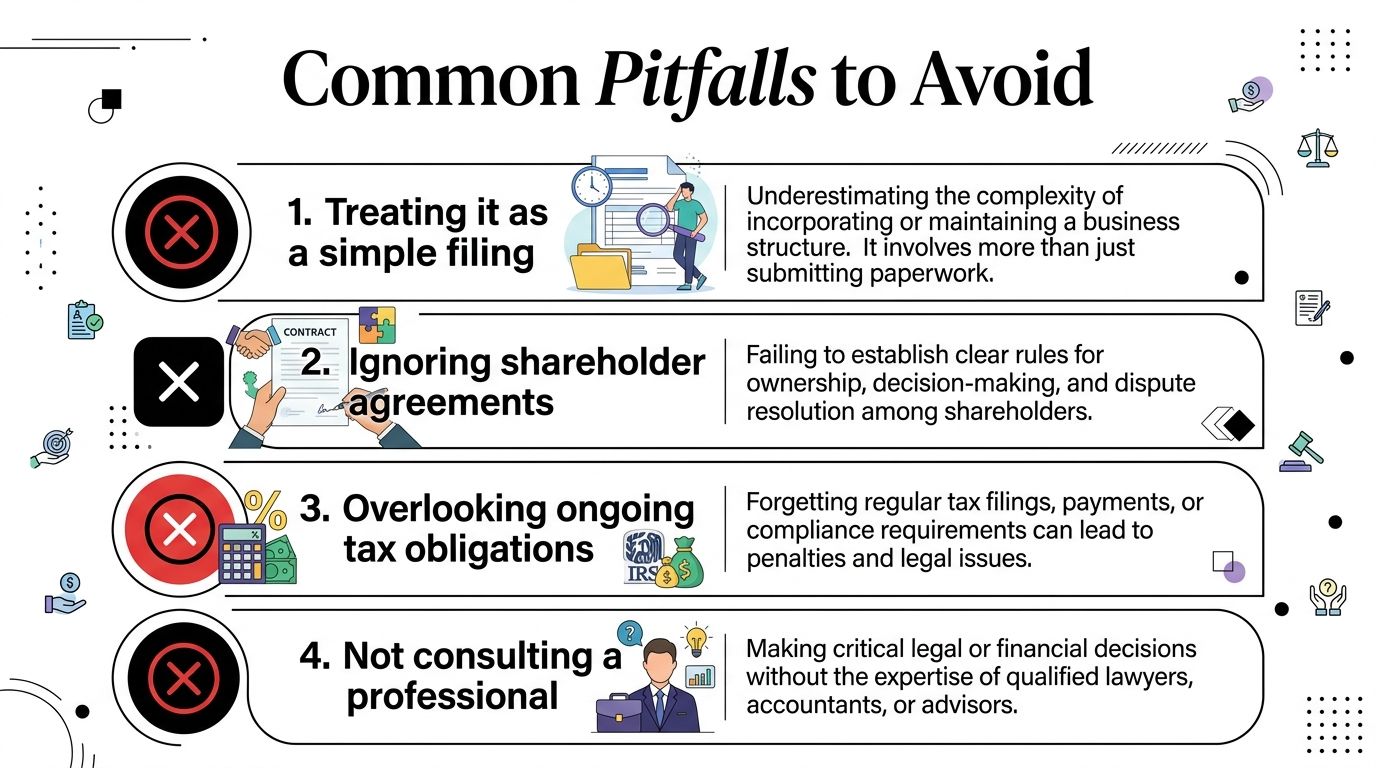
The most common mistake is assuming the conversion is the whole project. It is not. Owners who focus only on the filing often forget that the old corporation still has tax, contract, and recordkeeping consequences, and those loose ends can create more trouble than the restructuring solved.
Problems that show up after the papers are filed
One frequent issue is skipping lender or landlord consents. If a loan agreement or lease requires approval before a transfer or change of control, the conversion can trigger a default problem if the consent is not handled first. Another is failing to retitle key assets, which leaves real estate, vehicles, or IP stuck in the wrong entity name long after the LLC is live. Tax planning is another common gap, and it is the one that tends to hurt the most because the consequences can be immediate and expensive.
Recent guidance on conversions also emphasizes the practical friction after the legal change, including material agreements, license reissuance, and EIN handling. The market has also seen a lot of attention on LLC-to-corporation moves for fundraising and QSBS planning, which makes the reverse move, back to an LLC, a second-order decision that often follows a change in business strategy rather than a simple preference shift (DWT). For some owners, the smarter move is not conversion at all, but restructuring ownership or distributions while preserving the corporate shell.
When counsel usually makes sense
- Appreciated assets: If the business owns valuable equipment, IP, or real estate, the tax and title issues need coordinated review.
- Debt and contracts: If lenders, landlords, or major vendors have consent rights, the deal documents need to be checked before filing.
- Multi-state operations: If the business crosses state lines, the compliance footprint is bigger than a single Georgia filing.
- Complex ownership: If there are multiple shareholders, buy-sell terms, or family ownership issues, a DIY filing can create disputes later.
- Timing pressure: If the business needs the conversion to line up with financing, sale activity, or a major operating change, the sequence matters.
That is where a Georgia business attorney earns the fee. The value is not just document preparation, it is spotting the traps before they become delays, defaults, or tax surprises. For a business owner in Cumming, Alpharetta, Forsyth County, or Fulton County, the right question is whether the conversion can be done, but whether it should be done at all, and under what structure.
If you're weighing a conversion, Miles Hansford Law Firm can help you evaluate the legal and operational trade-offs, coordinate the filing path, and avoid cleanup problems that surface after the entity change. Visit Miles Hansford Law Firm to schedule a consultation and speak with a Georgia business attorney before you file.