


A car problem hits hard when money is already tight. In Cumming and Alpharetta, that usually means you still have to get to work, handle school pickup, and keep life moving while the lender is calling and the next payment feels impossible. Chapter 13 bankruptcy can give you a structured way to protect the vehicle, catch up on missed payments, and buy time under court supervision, but the right move depends on your loan, your income, and what else is happening in the case.
For many North Georgia families, the car is tied to everything else. Divorce, reduced household income, and child-related expenses often collide at the same time, which is why people in Forsyth County and Fulton County start looking for a practical answer instead of another lecture. If you're trying to decide whether to keep the car, reduce the payment burden, or walk away from a bad loan, this guide gives you the actual trade-offs.
Your Guide to Chapter 13 and Your Car Loan in Cumming GA
A client in Cumming may call after a repossession notice arrives or after the lender says the loan is already in default. The same panic shows up in Alpharetta, Suwanee, and Johns Creek, because losing a car can derail work, school pickups, and child exchanges in a hurry. Chapter 13 gives people with regular income a court-supervised way to get time, protect a vehicle in the case, and work out overdue payments without letting the lender keep pressing the account.
That matters even more after divorce or another life change has cut the household budget in half. One spouse may have kept the car, but both income and expenses have changed, and the loan no longer fits the new reality. Chapter 13 can fit that kind of situation because it lets you address car debt inside a broader repayment plan instead of trying to fix the problem payment by payment on your own.
For a person trying to hold on to transportation and still keep the rest of the household afloat, a key question is whether the car can be kept without putting the entire budget at risk. The federal courts explain that Chapter 13 is a repayment plan for individuals with regular income, and it generally lasts 3 to 5 years. If current monthly income is below the state median, the plan is usually 3 years. If it is above median, the plan is generally 5 years, and the Bankruptcy Code caps the plan at no more than 5 years (U.S. Courts chapter 13 basics).
That structure is why Chapter 13 is often the chapter people mean when they say they need to save the car. It does not erase the loan automatically, but it can place the debt into a court-approved process that gives the debtor room to catch up and make a realistic plan. If you are comparing vehicle financing terms before you commit to bankruptcy, Toya AI's car finance guide gives a plain-language look at how auto lending works.
If you are also weighing a non-bankruptcy solution, review the practical trade-offs in alternatives to bankruptcy. A rushed choice can leave you with the same loan stress and less room to recover.
Understanding How Chapter 13 Protects Your Vehicle
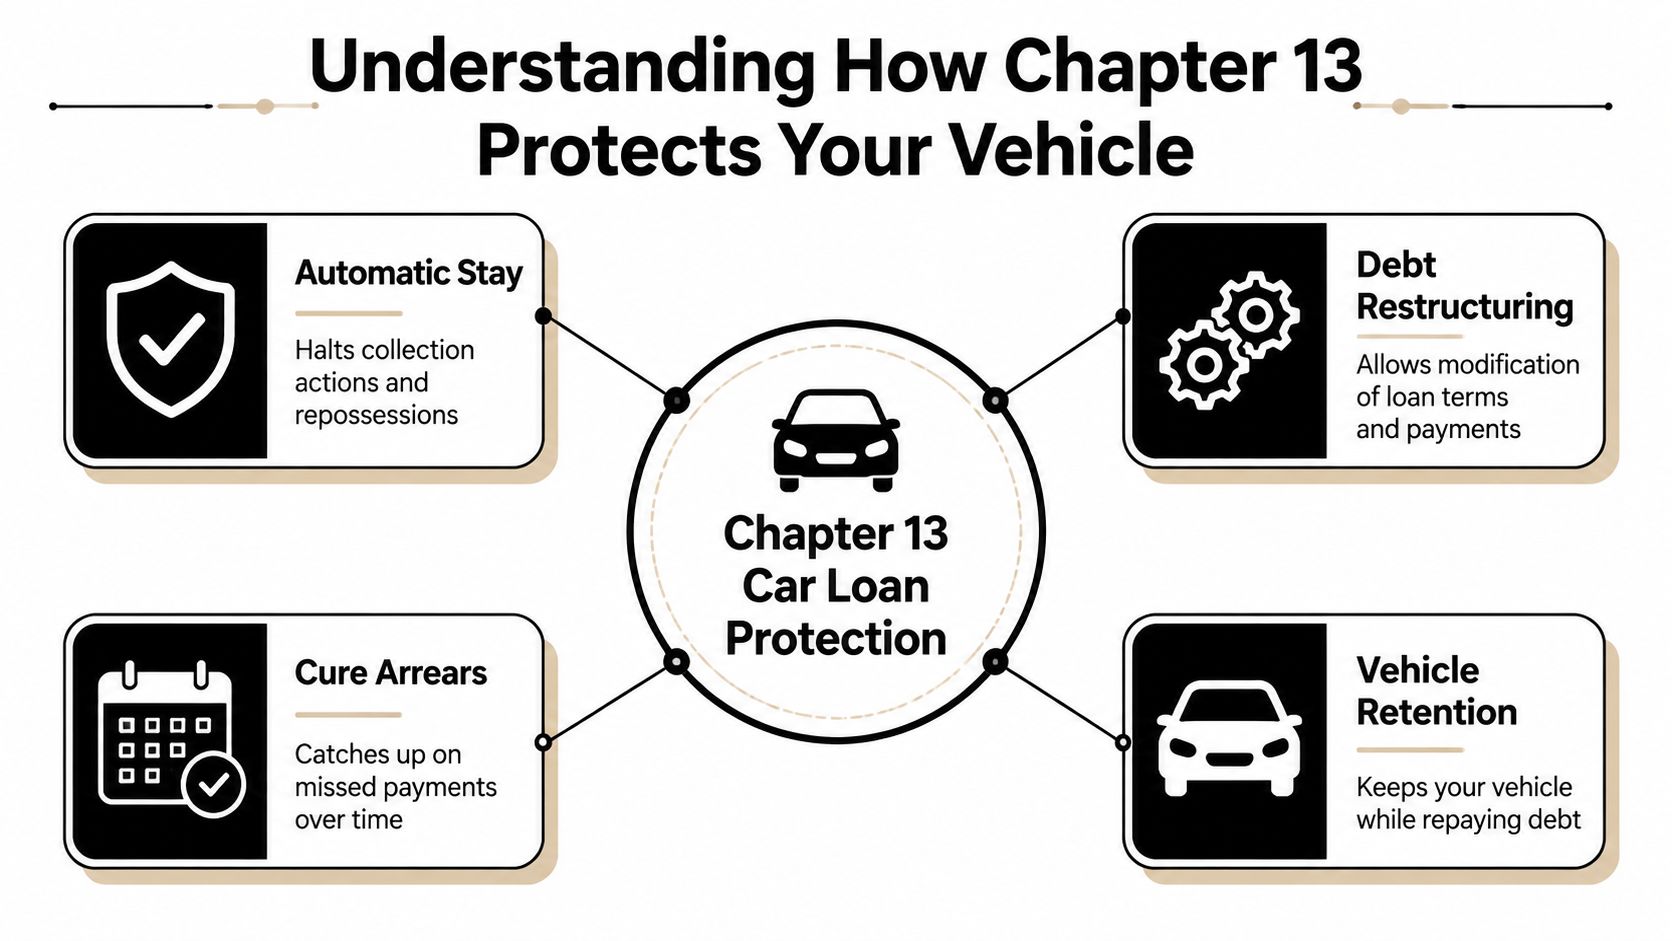
Chapter 13 changes how a car loan is handled during financial distress. Instead of dealing with a lender one missed payment at a time, you file a court-approved repayment plan and make payments through the case over time. That structure can keep a vehicle in place while past-due amounts are addressed inside the case, and creditors are generally blocked from starting or continuing collection efforts during bankruptcy (U.S. Courts chapter 13 basics).
How the payment structure works
The repayment plan is not a second car note added on top of an already strained household budget. It is a court-supervised payment system that collects what the plan requires and distributes funds under the terms the court confirms. Under Georgia practice, a Chapter 13 debtor usually makes plan payments for 3 to 5 years, and if the debtor's current monthly income is above the state median, the applicable commitment period is generally 5 years unless unsecured claims are paid in full sooner (Georgia Chapter 13 overview).
That matters for a chapter 13 car loan because the vehicle debt becomes part of a larger repayment picture. For someone in Roswell or Dawsonville, that can mean one monthly plan payment handles the arrears while the ongoing car payment is treated the way the plan requires. The goal is to keep transportation usable while the rest of the budget is under control, especially when divorce or another family-law issue has already disrupted the household.
A debtor who is already facing a collection lawsuit may also need to look at how fast a creditor can move before the bankruptcy case starts. debt collection lawsuit guidance helps explain why timing matters once collection pressure begins.
Why the legal protection matters
The immediate protection is the stay. Once the case is filed, lenders usually cannot keep collecting as if nothing changed. That breathing room is often what lets a family in Milton or Sandy Springs keep transportation while the legal case gets organized.
A Chapter 13 filing can also create room to reduce the secured part of a car debt in the right case, which is why people often ask about a powerful Chapter 13 bankruptcy tool when the loan balance is far above the vehicle's value. For a driver in Forsyth or Fulton County, the practical question is simple, whether the car can stay in the driveway without forcing the rest of the finances into deeper trouble.
Your Three Options Cramdown Reaffirmation or Surrender
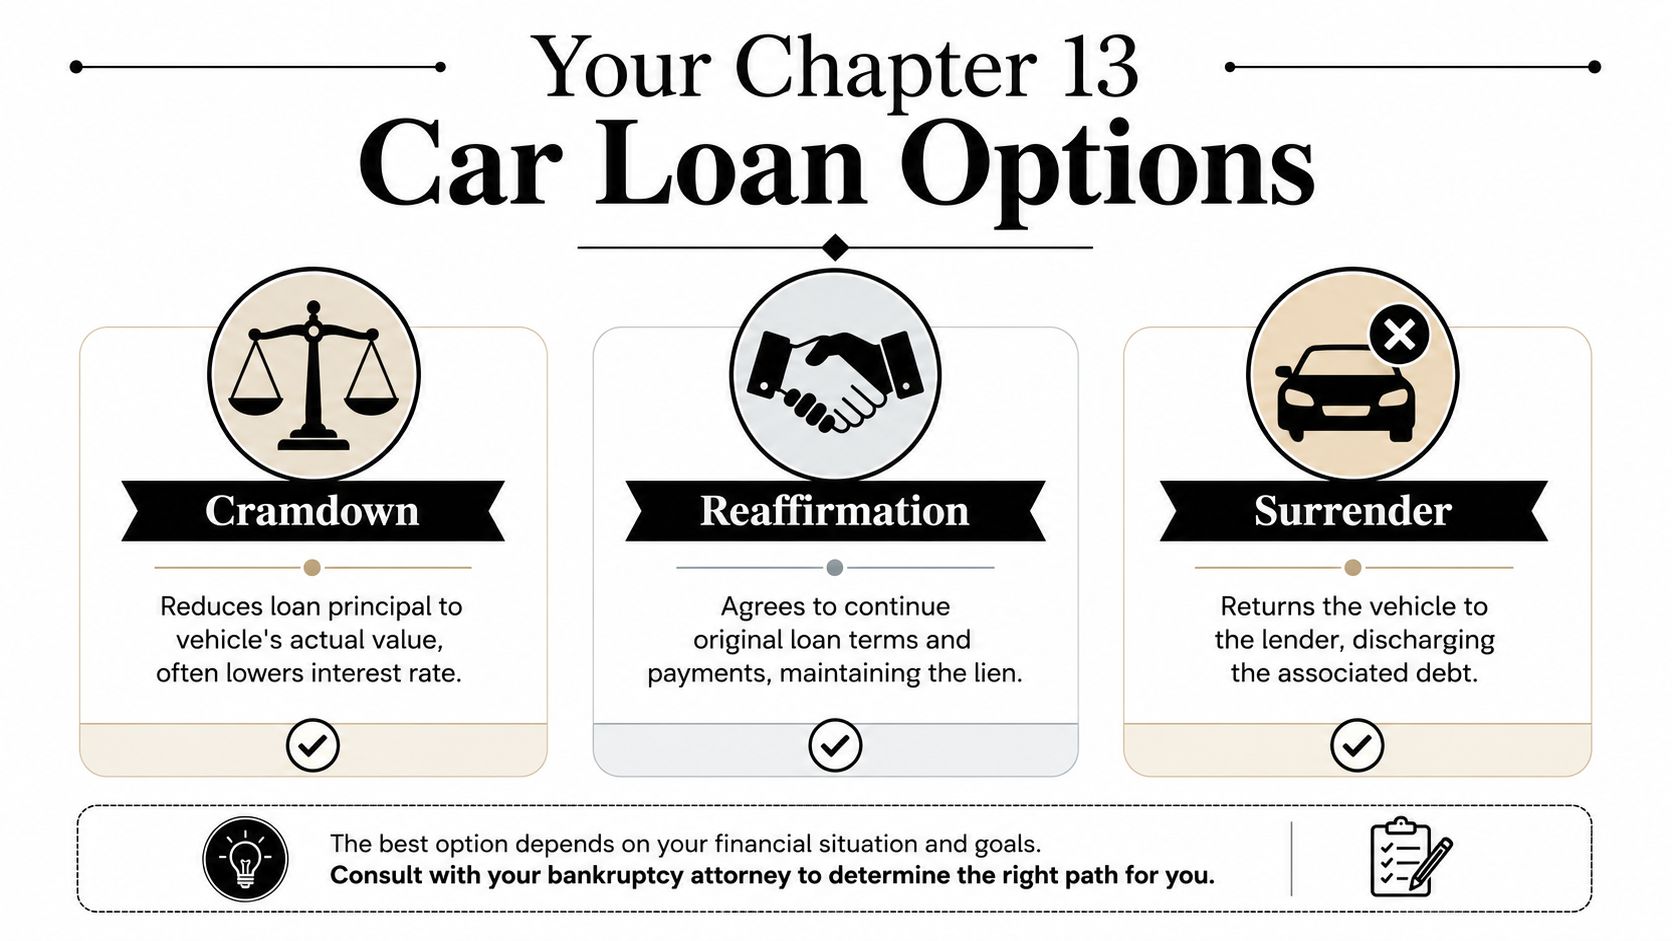
A car in Chapter 13 usually leads to one of three practical choices. The right answer depends on the car's value, the age of the loan, and whether the payment is realistic inside a budget that may already be strained by divorce or other family-law obligations.
Cramdown can reduce the secured claim
A cramdown may be available for a qualifying auto loan. The vehicle must have been purchased for personal use, and the debt has to be older than 910 days before filing. If those conditions are met, the loan can be reduced to the vehicle's fair market value, and the remaining balance is treated like unsecured debt, which typically gets a much lower repayment percentage in the plan (car loan cramdown rules).
Practical rule: the older the loan and the worse the negative equity, the more valuable a cramdown can be.
That's why a debtor in Cumming with a heavily upside-down car loan may get more relief than someone who just bought a vehicle last year in Alpharetta. The law doesn't create a magic discount for every car, but it can sharply change the secured part of the debt when the timing fits.
If you want a deeper explanation of the loan-reduction concept, the powerful Chapter 13 bankruptcy tool overview gives a plain discussion of cramdown itself.
Reaffirmation keeps the original deal in place
Reaffirmation means you choose to keep the loan and continue under the original agreement. That may make sense if the payment is manageable, the vehicle is reliable, and the balance is close to the car's actual value. It's less attractive when the payment is too high or the car has become a budget drain.
Surrender can be the cleanest financial move
Surrender is hard emotionally, but sometimes it's the smartest choice. If the payment is crushing cash flow, the car is unreliable, or you're trying to stabilize a household after divorce, walking away can stop a bad loan from dragging the rest of the case down.
For any of these options, it helps to understand the vehicle paperwork itself. If you're evaluating sale documents or title language, contract for selling a car is a useful companion resource.
The Approval Process in Forsyth and Fulton County Courts
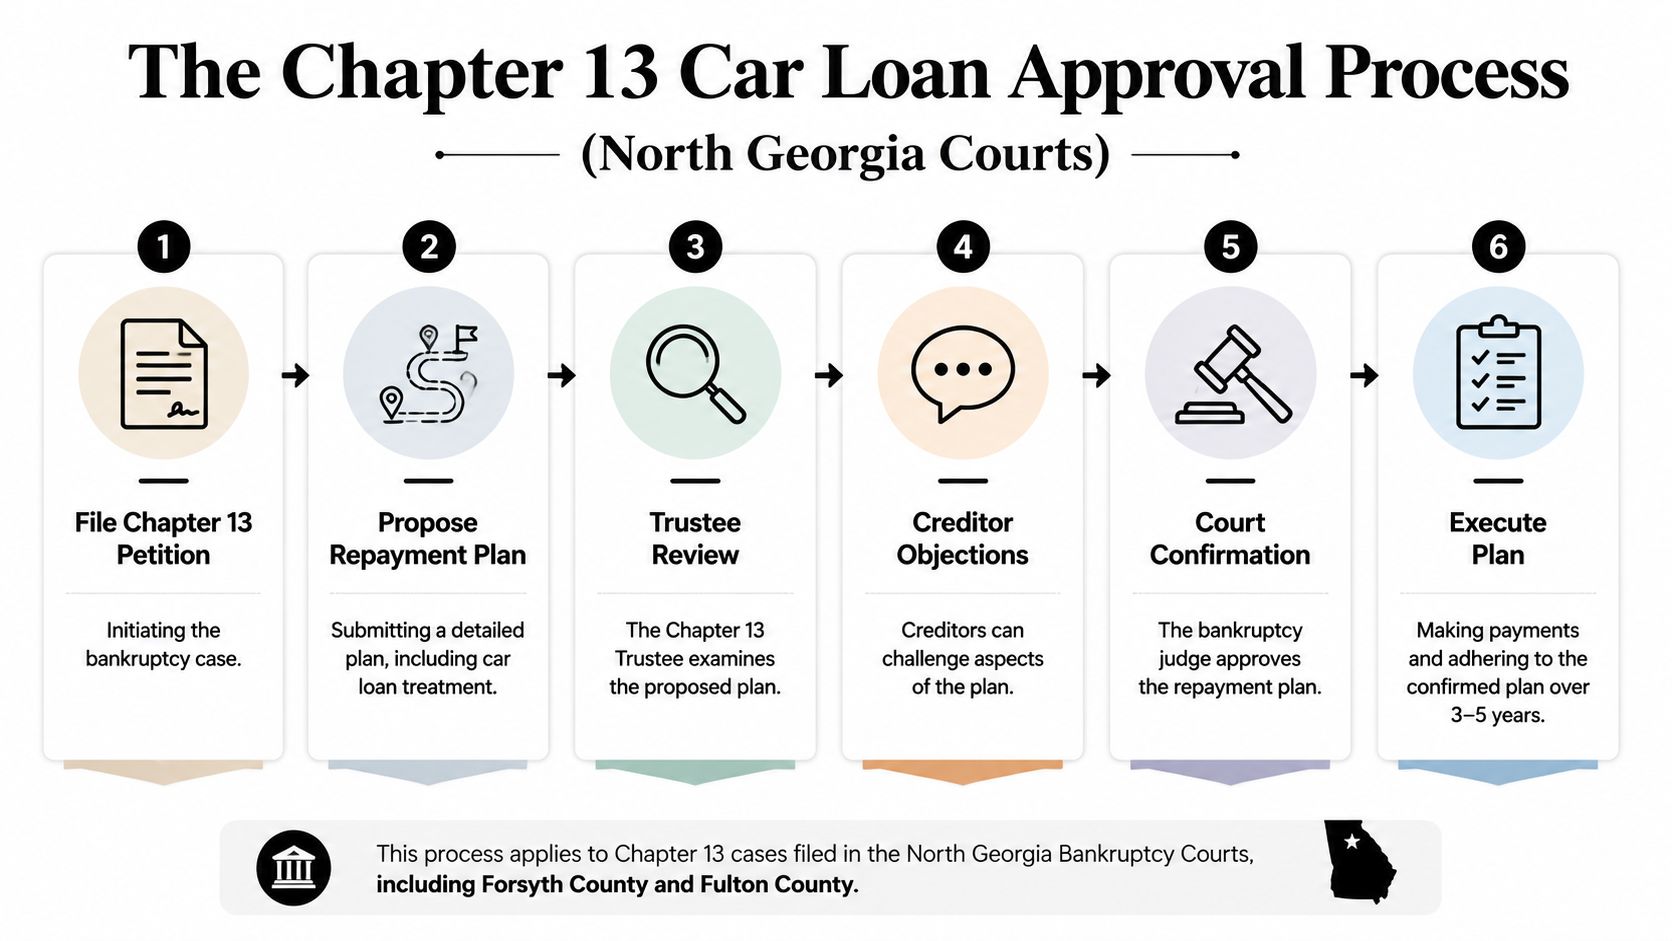
In Forsyth County and Fulton County, the approval process turns a Chapter 13 car issue into a court-reviewed payment structure. The filing has to match the plan, the trustee's review, and the judge's confirmation process, whether the case is in Cumming, Alpharetta, or elsewhere in North Georgia. If a divorce, reduced household income, or another life change has already strained the budget, the court still wants a plan that works on paper and in real life.
What gets reviewed
Missed car payments are usually not handled through a separate side deal. Chapter 13 lets debtors cure auto-payment arrears over the 3-to-5-year plan, and those arrears are folded into the secured claim calculation. As long as plan payments stay current, and any ongoing direct car payments are kept current too, the lender is generally protected from repossession.
That review matters in local practice because trustees and judges want to see whether the car treatment fits the rest of the case. If the payment is too high, the plan may fail. If the arrears are clearly documented and the income supports the budget, the vehicle can often remain in place. For a fuller explanation of how arrears are handled in Chapter 13, see Chapter 13 car-loan arrears treatment.
What you should expect locally
In Forsyth County divorce filings and Fulton County custody hearings, timing already affects household income and cash flow. A bankruptcy case sits on top of that reality. If temporary hearings, support issues, or property division are changing the monthly numbers, the car loan treatment has to be drafted with those pressures in mind. That is why local court familiarity matters in Forsyth County Superior Court, Fulton County Superior Court, and the surrounding North Fulton courts.
Court approval is not about making the car affordable in theory. It is about whether the budget still works after the loan is placed inside the plan.
If the plan also has to account for Georgia family-law issues like equitable division, parenting plans, or temporary support orders, the car payment cannot be treated in isolation. The filing has to survive the full financial picture, not just the auto lender's objection.
Can I Get a New Car Loan in Alpharetta During Chapter 13
Yes, but approval controls the process. If a vehicle fails during a case in Alpharetta or Sandy Springs, a debtor may need replacement financing, and that usually requires trustee or court approval before the new debt is taken on. The lender, the trustee, and the court need enough detail to decide whether the payment fits inside the confirmed plan.
What the court wants to see
A request for post-petition car financing usually needs to show the purchase price, the interest rate, and the monthly payment. Those details give the court or trustee a way to judge whether the proposed loan is affordable and reasonable before any new obligation is allowed (post-petition car purchase requirements).
That review matters because a new loan can upset an otherwise workable case if the payment is too high or the term is too aggressive. In a market where new-car payments have stayed high in recent reporting, affordability is often the main issue, not just approval, and used-car financing can still be expensive (bankruptcy and auto financing considerations).
The hidden budget problem
A recent Supreme Court interpretation held that Chapter 13 debtors cannot claim a car ownership expense deduction when they do not make loan or lease payments. That makes a new vehicle decision more than a transportation issue, because it can affect disposable income and whether the plan needs to be modified (Lexology summary of the decision).
A debtor in Johns Creek or Milton should think beyond the initial approval. A car loan that barely works at signing can still draw objections later if it throws the budget off balance. Sometimes the better choice is to repair the current vehicle, wait, or choose a lower-cost used car that does not put the plan at risk.
Why Choose Miles Hansford for Your Financial Fresh Start
Financial distress doesn't stay in one lane. It affects divorce negotiations, custody schedules, property division, and the ability to stay employed while the case moves forward. In Cumming, GA and Alpharetta, GA, that reality is familiar, and it's why careful legal strategy matters as much as paperwork.
Miles Hansford's North Georgia presence in Forsyth County, Fulton County, and the surrounding communities means clients can get local guidance that understands both family-law pressure and the financial strain that often comes with it. When a car loan, divorce, and parenting plan all intersect, the right approach is measured, protective, and grounded in the actual court process.
Frequently Asked Questions About Chapter 13 Car Loans in Georgia
Q: Can Chapter 13 stop a repossession in Cumming, GA
A: Yes, in many cases it can. The filing generally triggers the automatic stay, which pauses collection activity while the Chapter 13 case moves forward. In Forsyth County cases, timing is critical, especially if the lender is already moving toward repossession.
Q: Do I have to keep making my regular car payment during Chapter 13
A: Usually, yes, depending on how the plan is set up. The loan treatment may require ongoing direct payments along with plan payments for arrears. If those payments fall behind, the lender can seek relief even after the case starts.
Q: Can I buy a car while my Chapter 13 case is active in Alpharetta
A: Yes, but you normally need trustee or court approval first. The request should include the price, interest rate, and monthly payment. North Fulton courts want to know the new debt won't break the feasibility of the confirmed plan.
Q: What happens if my current car loan is upside down
A: A cramdown may help if the loan qualifies. For a personal-use vehicle, the debt must be older than 910 days before filing. If it qualifies, the secured claim can be reduced to the car's fair market value.
Q: Will Chapter 13 let me catch up on missed car payments
A: Yes. Chapter 13 lets debtors cure auto-payment arrears over the plan term, and those missed amounts are built into the secured claim calculation. That is often the main reason people in Forsyth County choose this chapter.
Q: How long does a Chapter 13 plan last in Georgia
A: It usually lasts 3 to 5 years. If current monthly income is below the applicable state median, the plan is usually 3 years. If it's above median, it is generally 5 years, unless unsecured claims are paid sooner.
Q: Does a divorce case affect my car loan treatment
A: It can. Divorce often changes income, household expenses, and support obligations, which affects whether a plan is feasible. In Fulton County and Forsyth County, car-loan strategy often has to be coordinated with custody, support, and property division issues.
If you're trying to protect a vehicle while managing divorce, custody, or mounting debt in Cumming or Alpharetta, speak with a local lawyer who understands both family law and the bankruptcy process. Schedule a consultation with Miles Hansford Law Firm today so you can review your options, protect your transportation, and move forward with a plan that fits your life.