


Meta Title: Estate Planning for Business Owners in Cumming, GA
Meta Description: Estate planning for business owners in Cumming, GA. Protect your company, family, and succession plan across Forsyth County and North Georgia.
Suggested URL Slug: /estate-planning-for-business-owners-cumming-ga
Schema Recommendations:
- Attorney
- LegalService
- FAQPage
Internal Link Suggestions:
- Georgia business succession planning
- What is a trust and how does it work
- What happens at a probate hearing
A business owner in Cumming, GA can spend years building something solid. Payroll gets met. Clients keep coming back. Vendors trust your name. Family members assume the company will always be there because you've always been there to carry it.
Then one unanswered question starts to matter more than most owners expect. What happens if you can't walk into the office next week?
For many entrepreneurs in Cumming, Alpharetta, Johns Creek, Milton, Suwanee, Dawsonville, Roswell, Sandy Springs, and Canton, the business is the estate. It isn't just an an asset on paper. It's income for your household, jobs for your staff, a cornerstone for future retirement, and often the legacy you hoped to hand down.
That is why estate planning for business owners has to do more than distribute property after death. It has to protect continuity during illness, incapacity, family transition, ownership disputes, and tax exposure. A good plan gives your family and your company instructions. A weak plan leaves them with guesswork.
Your Life's Work Deserves a Fortress Not a Gamble
A familiar North Georgia story looks like this. The owner started small, maybe with a service company in Cumming, a medical practice near Alpharetta, or a closely held company serving clients from Roswell to Suwanee. The business grew because the owner made the calls, approved the hires, signed the checks, negotiated the contracts, and carried key customer relationships personally.
Everything worked while the owner was available.
Then a health event, a long recovery, or a sudden death exposed the underlying structure. No one had authority to sign on the operating account. The spouse knew the business mattered but didn't know where the governing documents were. The co-owner thought he knew the succession plan, but nothing was written clearly. Adult children had expectations that didn't match each other, or the owner's actual wishes.
Practical rule: If your business only functions because everyone assumes you'll be there tomorrow, you don't have a succession plan. You have a dependency.
Business owners typically come to realize the problem isn't abstract. It isn't just about taxes or paperwork. It's about whether your family has liquidity, whether employees stay, whether a surviving partner can keep operations stable, and whether years of value get preserved or dismantled under pressure.
The encouraging part is that these risks are manageable. With the right legal documents, ownership rules, and incapacity planning, a business in Forsyth County or Fulton County can move through a hard transition with far less disruption. The difference usually isn't luck. It's whether the owner planned while they still had choices.
Why Estate Planning Is Mission-Critical for Business Owners in Cumming and Alpharetta
Owners in Cumming and Alpharetta often assume estate planning can wait because the company is healthy and the family is getting paid. The risk usually arrives earlier. Incapacity, not death, is often the event that exposes the weakness in the plan.
The local stakes are higher than many owners think
In this part of North Georgia, a large share of business wealth sits inside closely held LLCs, partnerships, and family companies. The owner may control banking access, customer relationships, hiring decisions, and contract approval personally. If that owner cannot act for six months after a stroke, surgery, or cognitive decline, the business can face a legal authority problem before it faces a tax problem.
That distinction matters in Georgia. A spouse does not automatically gain management rights in an LLC. An adult child who understands the company may still have no authority to sign checks, approve payroll, or deal with lenders. In a partnership, the governing agreement may restrict transfers or decision-making in ways the family never expected. In Forsyth County and Fulton County, those issues can become urgent fast because banks, buyers, vendors, and employees usually want written authority, not family consensus.
The pressure points tend to show up all at once:
- Operations slow down: payroll, vendor payments, and contract approvals can stall if no one has clear signing authority.
- Control separates from value: heirs may receive an ownership interest without the right or ability to manage the company.
- Liquidity problems surface: the family may need income immediately while the business remains hard to sell or refinance.
- Disputes get expensive: unclear transfer rules often turn a private business issue into probate, litigation, or both.
I often tell owners the same thing. The plan has to answer two separate questions. Who gets the value, and who has authority to act on day one of a crisis.
What works and what usually fails
The plans that hold up under pressure coordinate the estate documents with the company documents. The plans that fail usually treat them as separate projects.
| Risk area | What usually fails | What works better |
|---|---|---|
| Incapacity during ownership | A generic financial power of attorney that does not clearly address business authority | Entity documents and incapacity planning that name who can manage, vote, sign, and access records |
| Ownership transfer | A will that leaves "everything equally" without addressing the business | A coordinated transfer plan that separates economic benefit from management control |
| Co-owner transition | Verbal promises about buyouts or succession | Written buy-sell terms, funding strategy, and valuation rules |
| Family expectations | Assuming relatives will work it out informally | Written instructions that match the operating agreement, trust terms, and actual roles in the business |
For many North Georgia owners, the hardest trade-off is fairness versus continuity. Leaving equal value to children may be appropriate. Leaving equal control usually is not, especially if only one child works in the business or a nonfamily manager keeps the company running. Good planning addresses that tension directly instead of pushing it onto the family after a crisis.
Georgia-specific succession planning for LLCs and closely held companies also requires attention to the operating agreement, transfer restrictions, voting rights, and the authority granted under powers of attorney and trusts. A generic online estate plan will not address those points well. Owners who want a more detailed look at that issue should review this guide to Georgia business succession planning for LLCs and family companies.
Business owners in Forsyth County usually do not need more paper. They need documents that work together under Georgia law, including during incapacity, when the wrong gap can threaten both the company and the family income.
Core Components of a Georgia Business Owner's Estate Plan
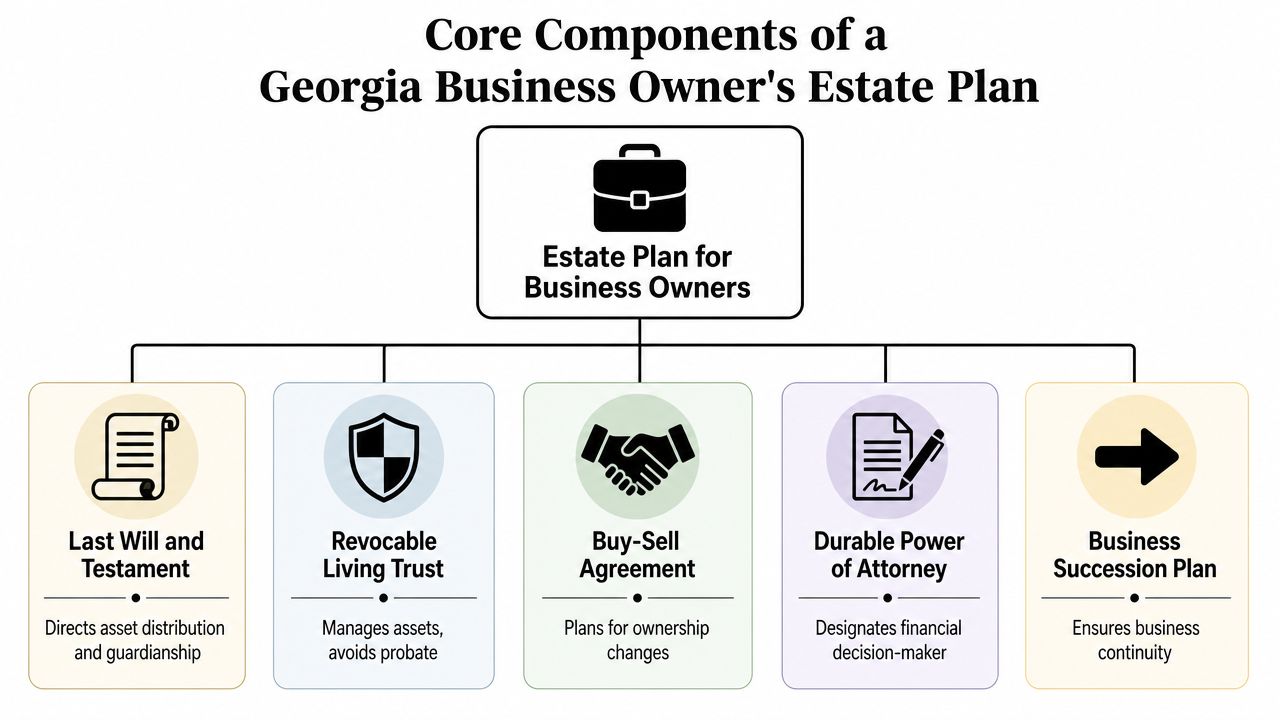
A business owner's estate plan succeeds or fails on coordination. The will, trust, power of attorney, operating agreement, buy-sell terms, and beneficiary designations each control a different part of the problem. If they conflict, your family and your company pay for the mismatch.
The documents that carry the load
A Last Will and Testament still has a job. It names fiduciaries, catches assets left outside the trust, and gives probate instructions. For a business owner, though, a will is often a backstop rather than the main control document, especially if the company needs someone to act before the probate court can appoint authority.
A Revocable Living Trust often works better for ownership continuity. If business interests are properly transferred to the trust, the successor trustee can step in under the trust terms rather than waiting for the estate process to catch up. That can matter a great deal in closely held companies where one person approves distributions, signs checks, or controls voting rights.
A Durable Power of Attorney covers lifetime authority. This document lets your agent act while you are alive, including during a stroke, cognitive decline, serious injury, or a period when you cannot manage the business. In my experience, incapacity creates more immediate chaos than death because the owner is still here, but no one is sure who can sign, access accounts, or make binding decisions.
Georgia owners also need to remember a hard truth. A power of attorney that looks broad on paper may still fail in practice if the bank, vendor, CPA, or co-owner agreement does not line up with it.
The business-specific pieces many owners skip
The Buy-Sell Agreement sets the exit rules before relationships are under strain. For LLCs and partnerships in Georgia, this is often the document that determines whether a disabled owner keeps an income stream, whether surviving owners can force a purchase, and whether heirs receive cash instead of unwanted management rights.
A strong buy-sell agreement usually addresses four points clearly:
- Transfer limits. Who can receive shares, units, or partnership interests, and which transfers require consent.
- Valuation. How the interest is priced so the family is not trapped in a fight over value after a death or disability event.
- Triggering events. Death, incapacity, retirement, divorce, bankruptcy, deadlock, and voluntary departure should not all be treated the same way.
- Funding. Insurance may cover some events. Installment payments, sinking funds, or lender approval may matter for others.
For Georgia LLCs, the operating agreement must match those terms. If the buy-sell agreement says one thing and the operating agreement says another, you have created an avoidable dispute.
The succession layer beyond the documents
A Business Succession Plan answers a different question. Who takes over, and on what terms?
That issue is larger than inheritance. It requires a practical division of authority, economics, and day-to-day responsibility. An owner may want a spouse to receive income, a child active in the company to control operations, and a nonfamily executive to keep the business stable during the transition. Those goals can work together, but only if the documents say so with precision.
I usually have owners sort the business into four buckets:
Decision-making authority
Who can vote ownership interests, approve major transactions, and bind the company?Cash flow rights
Who receives distributions, salary continuation, or sale proceeds?Operational responsibility
Who runs payroll, supervises employees, handles customers, and keeps contracts in force?Exit terms
If an heir, spouse, or co-owner wants out, how is that interest redeemed without damaging the company?
That framework is especially important in Forsyth and Fulton County matters involving family LLCs, professional practices, and owner-managed companies. Georgia law gives you room to shape these outcomes, but only if the governing documents are drafted together and reviewed against the actual structure of the business. Owners who want a closer look at that issue should review Georgia business succession planning for LLCs and family companies.
Tax planning belongs in the conversation too, even when tax is not the main risk. A poorly structured transfer can create pressure to sell assets, redeem interests at the wrong time, or distribute value unevenly among family members. For a general tax background, see Expert insights on inheritance tax.
Advanced Strategies for Tax Minimization and Incapacity Planning
A founder in Alpharetta has a stroke on Tuesday. By Wednesday, payroll needs approval, a lender wants updated financials, and a key customer is waiting on a signed change order. If no one has clear legal authority to act for the company while the owner is still living, the business can stall at the exact moment stability matters most.
The incapacity gap most owners don't see
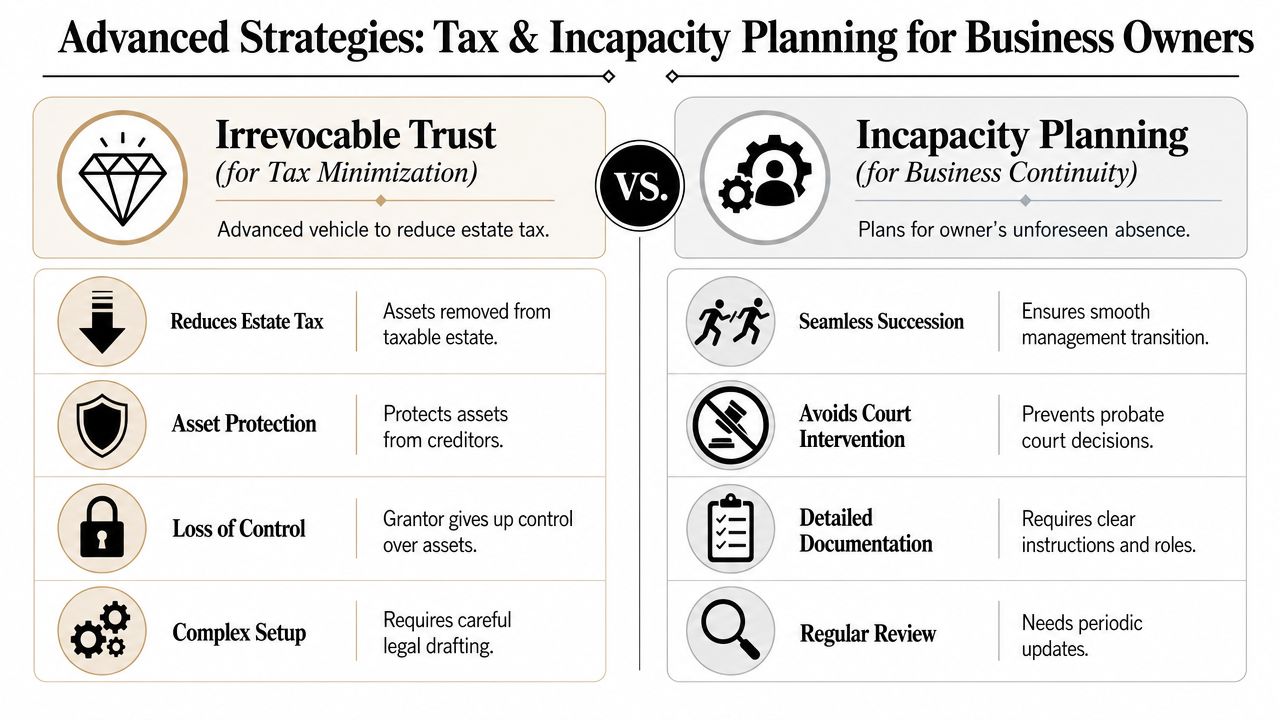
In practice, incapacity creates harder short-term problems than death. Death triggers a transfer process. Incapacity creates limbo. The owner is still here, but may be unable to sign checks, direct employees, approve tax filings, or deal with banks that insist on current authority documents.
That issue shows up often with Georgia LLCs and partnerships. A personal durable power of attorney may not be enough if the document is vague, outdated, or inconsistent with the operating agreement, partnership agreement, banking resolutions, or internal company procedures. In Forsyth and Fulton County matters, I often see families learn too late that authority over an ownership interest is not the same as authority to run daily operations.
A business continuity plan should answer three separate questions clearly:
- Who can act for the owner during temporary or long-term incapacity?
- What specific powers does that person have with respect to payroll, banking, contracts, taxes, and employees?
- Do the entity documents and third-party records recognize that authority?
A well-drafted trust can also play a major role here, especially if ownership interests are already positioned for management continuity. Owners who want the fundamentals should review how a trust works in an estate plan.
Tax planning for closely held companies
For owners with a company that is likely to grow, the main tax objective is usually straightforward. Move future appreciation out of the taxable estate without giving up more control than the family is willing to surrender.
One option is a Beneficiary Defective Irrevocable Trust, or BDIT. As discussed in Spencer Fane's review of estate planning considerations for business owners, this structure can help transfer appreciating business interests outside the owner's estate while preserving meaningful planning flexibility. The trade-off is complexity in administration, trustee selection, and coordination with transfer restrictions inside the business itself.
Valuation also matters. For partial transfers of closely held business interests, minority and marketability discounts may reduce reported transfer value when the facts and appraisal support them. The IRS examines these positions closely, so owners should treat discount planning as an appraisal and documentation issue, not a shortcut. A transfer that looks reasonable inside the family can fail under scrutiny if the company records, governing documents, and valuation report do not line up.
Liquidity planning belongs in this discussion too. Life insurance, if owned in the right structure, can supply cash for taxes, redemptions, or equalization among children when only one child will continue in the business. Owners sorting through transfer-tax terminology often benefit from Expert insights on inheritance tax because families frequently confuse estate tax, inheritance tax, basis rules, and business succession planning.
What advanced planning usually requires
Good planning documents do not work in isolation. They must match the company on paper and in practice.
- Trust planning has to fit the entity documents. A transfer that violates an LLC operating agreement or partnership restrictions can trigger disputes or void the intended result.
- Appraisals must be defensible. If a transfer depends on discounted value, qualified valuation support is part of the plan.
- Control and benefit should be separated intentionally. The person managing the company, the people receiving economic benefit, and the person serving as trustee do not always need to be the same.
- Incapacity instructions should be tested against real operations. If the acting agent cannot get access to the bank, CPA, payroll provider, and major vendors, the document set is incomplete.
- Reviews should happen after major changes. Growth, refinancing, a new partner, divorce, illness, or a move to a different tax posture can all require revisions.
For North Georgia owners, that coordination is where many plans succeed or fail. The goal is not solely to reduce taxes. The goal is to keep the business operable, keep control where it belongs, and keep a family from asking the Forsyth or Fulton County courts to solve a problem that should have been handled privately.
Navigating Georgia Law and the Forsyth County Probate Process
A business owner in Forsyth County has a stroke on Monday. Payroll is due Thursday. The family knows the company is valuable, but no one is sure who can sign checks, approve distributions, or vote the owner's LLC interest. That crisis reaches the courthouse faster than many owners expect.
Georgia law gives a great deal of control to the documents that govern the business. For LLCs and partnerships, the operating agreement or partnership agreement often determines who may manage, who receives only economic rights, whether an interest can transfer at all, and what happens if an owner becomes incapacitated. If those terms are missing or vague, Georgia default rules and court proceedings start filling the gaps.
Entity documents control more than owners expect
I often see owners focus on who inherits the business and miss the more immediate question of who can act for the business during incapacity. In practice, incapacity causes more operational disruption than death because the owner is still alive, the bills still need to be paid, and the authority problem is often less clear.
For a Georgia LLC, that means the operating agreement should address management succession, voting rights, transfer restrictions, and whether a successor receives control rights, economic rights, or both. Partnerships need the same level of precision. Without it, family members, co-owners, banks, and advisors may each take a different view of who is in charge.
That is how profitable companies get pulled into avoidable disputes.
What probate involvement can look like in Forsyth County or Fulton County
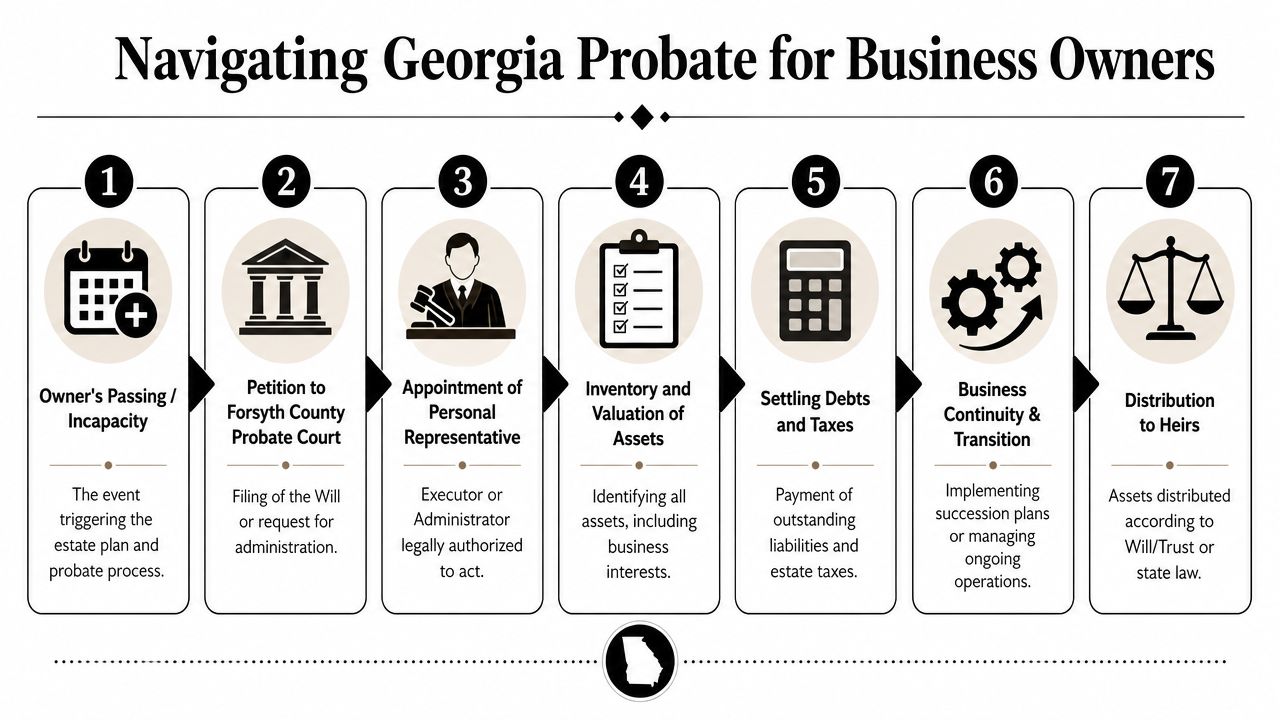
If an owner dies with assets titled in his or her name, the estate may need action through the probate court to establish authority and move property. In Forsyth County and Fulton County, that can mean offering a will for probate, appointing a personal representative, identifying business interests, gathering valuations, addressing creditor issues, and determining what rights passed to the estate.
For a business, delay has a price. Vendors still expect payment. Employees still expect direction. Co-owners may need consent for decisions that cannot wait.
Common pressure points include:
- Bank and account access: Financial institutions usually want current, written authority before they release funds or honor instructions.
- Management disputes: Surviving members or partners may disagree over whether the estate received governance rights or only financial rights.
- Business valuation fights: The estate, co-owners, and tax advisors may use very different numbers for the same company.
- Court involvement during incapacity: If no effective power of attorney or governing-document solution exists, a conservatorship or related proceeding may be required before someone can act.
Anyone trying to understand the court process in more concrete terms can review what happens at a probate hearing in Georgia.
The better result is to leave as little as possible for the probate court to sort out. In my experience, owners in Cumming and Alpharetta are best protected when their estate plan and entity documents work together so authority passes privately, quickly, and with as little room for dispute as possible.
Common Pitfalls and How Our Cumming Attorneys Can Help
A common call to our office starts the same way. The owner is still alive, but in the hospital, and no one can sign payroll, approve a loan draw, or deal with the bank because the legal authority was never set up correctly. Death planning matters, but for many Georgia business owners, incapacity is the event that exposes the weakest part of the plan first.
The first mistake is false confidence. Signed documents do not mean the business can keep operating. I regularly see plans that look finished in a binder but fail under real pressure because the trust was never funded, the operating agreement was never updated, or the person named under a power of attorney lacks clear authority to handle company interests.
Where plans usually break down
An unfunded trust is one of the most common problems. The owner signs the trust, then leaves the LLC or partnership interest in his or her individual name. The result is predictable. The trust cannot control what it does not own.
Outdated governing documents cause just as many disputes. A buy-sell agreement drafted years ago may use an old valuation method, miss disability or incapacity triggers, or conflict with the company's current ownership structure. In Forsyth and Fulton County matters, those gaps often become expensive at the worst possible time, especially if family members expect control that the entity documents do not give them.
Another frequent error is treating a will as the main business succession tool. A will can transfer an ownership interest at death. It does not solve management authority during incapacity, restrictions on transfer under a Georgia LLC operating agreement, or the practical question of who steps in tomorrow morning to make decisions.
Sometimes the problem is simpler and just as serious. The wrong person has been named to act. A capable adult child may be trustworthy with personal finances but have no experience dealing with vendors, employees, tax filings, or co-owners.
How these problems get addressed
The fix is coordination. The will, trust, financial power of attorney, advance directive, operating agreement, partnership agreement, insurance design, and succession instructions need to work together under Georgia law.
For LLC owners, that often means reviewing whether the documents separate economic rights from management rights and whether the company has written consent rules for an owner's incapacity. For partnerships, it means checking what the agreement says about authority, withdrawal, continuation, and buyout rights before a crisis tests those provisions.
Miles Hansford Law Firm advises clients in Cumming, Alpharetta, Forsyth County, and Fulton County on how estate planning documents and business documents interact in practice. That includes identifying gaps that could force family members into avoidable court proceedings, trigger disputes with co-owners, or leave a company without valid decision-making authority during a medical emergency.
A strong review is not about producing more paper. It is about making sure your family can protect the business, your partners know the rules, and your company can keep functioning if you are gone or if you are here but cannot act.
Frequently Asked Questions About Business Estate Planning in Georgia
Q: Do I need estate planning if my business is small in Cumming, GA?
A: Yes. Size doesn't remove the risk. If you're the person who signs contracts, manages bank access, or controls customer relationships, a disruption can hit even a small company hard. In Cumming and throughout Forsyth County, the right plan usually addresses ownership, authority, and business continuity, not just who inherits assets.
Q: What's the first document most business owners in Alpharetta should review?
A: Start with the operating agreement, partnership agreement, or shareholder documents. In Alpharetta and across Fulton County, those records often control what happens if an owner dies, becomes incapacitated, or wants to exit. If those provisions don't match your will or trust, the conflict can create expensive delays.
Q: Can a revocable living trust avoid probate for my business interest in Georgia?
A: It can help, but only if the business interest is properly transferred into the trust and the entity documents allow that structure. In Georgia, funding matters as much as drafting. Owners in Cumming and Alpharetta often discover too late that a signed trust alone doesn't change title.
Q: Why is incapacity planning so important for business owners near me?
A: Because death isn't the only trigger event that threatens the company. If you're alive but unable to act, payroll, contracts, tax filings, and banking authority can all be affected. A durable power of attorney and business-specific continuity instructions often prevent a temporary medical crisis from becoming an operational collapse.
Q: Should family members inherit equal shares of the business?
A: Not automatically. Equal ownership can create tension if only one family member works in the business or understands operations. In Georgia business succession planning, it's often better to separate management rights, economic benefits, and buyout options so the plan reflects real roles instead of assumed fairness.
Q: Do multi-owner businesses in Forsyth County need a buy-sell agreement?
A: In most cases, yes. A buy-sell agreement helps define who can acquire an owner's interest, how the interest gets valued, and what happens after death, incapacity, retirement, or dispute. Without those rules, surviving owners and heirs may be left negotiating under pressure.
Q: Will probate court decide what happens to my company if I have no plan?
A: Probate court may become part of the process if authority isn't clear or assets pass through the estate. In Forsyth County Probate Court or Fulton County Probate Court, that can mean added delay, valuation issues, and uncertainty about who may act for the business. Planning ahead keeps more control private.
If you own a business in Cumming, Alpharetta, Forsyth County, Fulton County, or the surrounding North Georgia area, now is the time to tighten the plan before a crisis makes the decisions for you. Miles Hansford Law Firm helps business owners protect their companies, families, and succession goals with practical Georgia estate planning. Schedule a consultation, speak with an attorney, and put clear authority in place while you still control the timeline.