


If you built a company in Alpharetta, bought rental property in Cumming, or spent decades turning cash flow into real wealth across North Georgia, you've probably asked the hard question at least once, who pays the tax bill when I'm gone, and will my family have to sell what I spent a lifetime building? That's the issue most families miss until it's too late. The right plan doesn't just reduce tax, it protects liquidity, control, and the legacy your family depends on.
Why Estate Tax Planning Demands Your Attention Now
A North Georgia family can do everything right, build a healthy business, own appreciating real estate, keep debt low, and still face a tax bill that puts the estate under strain. The danger is liquidity. Heirs may inherit valuable assets on paper and still have no easy way to pay the tax without selling something the family intended to keep.
That is why the current planning window matters. In the United States, the Tax Cuts and Jobs Act raised the basic exclusion amount from $5.6 million per person in 2018 to $13.99 million per person by 2025, or $27.98 million for a married couple, and that higher exemption exists within a narrow window before the rules change or reset (The Tax Adviser). For families in Cumming, GA and Alpharetta, GA, waiting can mean losing transfer capacity that may not be available later.
Families that plan early are usually the ones that keep control. They see the size of the exposure and refuse to leave the outcome to chance.
The federal estate tax reaches only a small slice of decedents, but that does not make it safe to ignore. The Urban-Brookings Tax Policy Center estimated that for 2022, only about 7,600 estate tax returns were filed nationwide, about 3,900 were taxable, and only about 0.14% of decedents paid estate tax (Tax Policy Center). That concentration is exactly why high-net-worth families in Forsyth County, Fulton County, and across North Georgia need targeted planning instead of generic advice.
If your wealth is tied up in a business, farm, or concentrated asset, you need a plan that protects cash flow as well as control. That means looking at liquidity before death, not after. It also means weighing estate tax reduction against the step-up in basis tradeoff, because aggressive transfer planning can shift tax cost rather than eliminate it. For families that hold gold, a separate review like the Antwerp Diamond gold tax guide shows how concentrated assets can create their own tax consequences, which is exactly why asset protection and estate tax planning should work together. Miles Hansford helps families build a plan that fits local realities, and the right answer starts with protecting the assets your family may need to keep.
Understanding Federal Estate and Gift Tax Exemptions
The federal estate tax, gift tax, and generation-skipping transfer tax work together as one system. That matters because the IRS doesn't let you ignore one bucket while using another. If you make lifetime gifts, you usually reduce what's available later at death.
For 2025, the federal estate-and-gift tax exemption is $13.99 million per individual and $27.98 million for a married couple, and it is scheduled to rise to $15 million per person in 2026, or $30 million for married couples, under current law and inflation indexing assumptions (JPMorgan Private Bank). The annual federal gift tax exclusion is separate. It sits at $19,000 per recipient in 2025 and 2026, and married couples can use gift-splitting to transfer $38,000 per recipient in a year without using any lifetime exemption (Edward Jones).
Federal Estate and Gift Tax Exemption Summary
| Category | 2025 Amount | 2026 Projected Amount |
|---|---|---|
| Federal estate-and-gift tax exemption, individual | $13.99 million | $15 million |
| Federal estate-and-gift tax exemption, married couple | $27.98 million | $30 million |
| Annual gift tax exclusion, per recipient | $19,000 | $19,000 |
| Annual gift tax exclusion with gift-splitting, per recipient | $38,000 | $38,000 |
Portability is another important lever. It allows a surviving spouse to use a deceased spouse's unused exemption, but it only helps if the family preserves that option through proper planning and filings. Don't assume the survivor can clean up the paper trail later. In Forsyth County and Fulton County, that kind of delay can leave real money on the table.
A useful way to think about exemption planning is this. The exemption is not a trophy to admire, it's a tool to deploy. If your estate is likely to grow, the decision to transfer now versus later can matter far more than people expect.
For readers who also own appreciating assets outside Georgia, the mechanics can look similar, but the local implementation still matters. A practical resource on the capital gains side is the Antwerp Diamond gold tax guide, especially if you're comparing income-tax treatment against transfer-tax planning. The point is simple. Know your exemption. Use it intentionally.
Trust Structures That Shield Your Wealth
Trusts are where serious planning starts. A will alone doesn't shield appreciating assets from future transfer taxes, and a revocable trust won't do it either. The right irrevocable structure provides flexibility or control, depending on what your family needs.
Choose the trust to fit the family problem
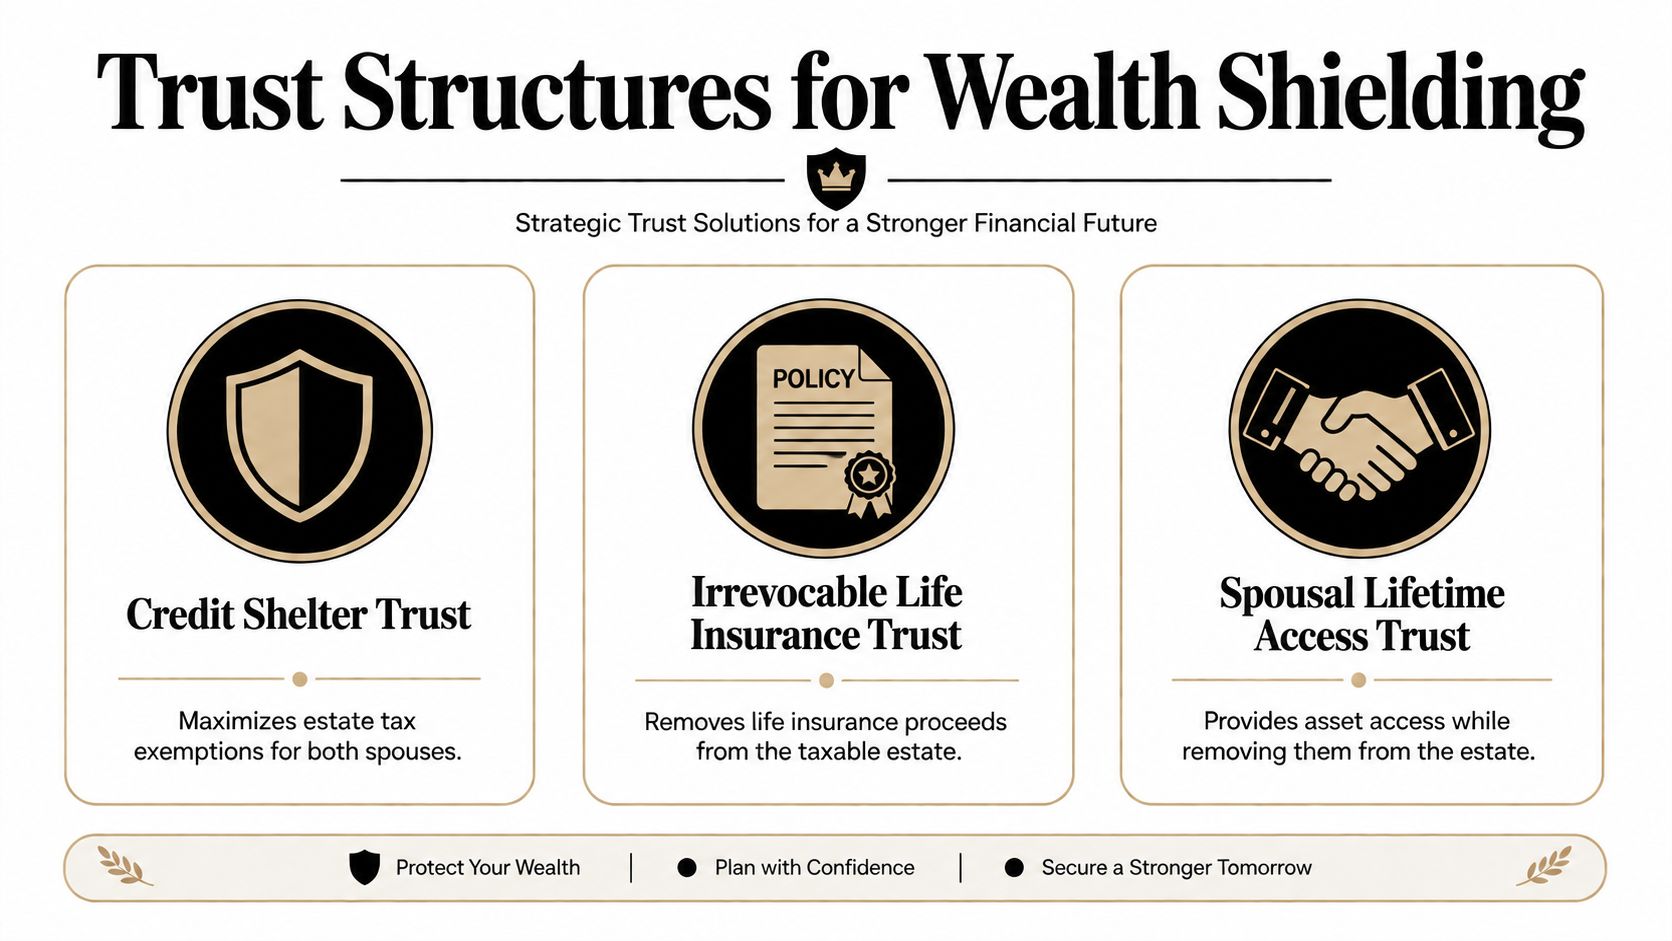
A credit shelter trust works best when both spouses want to maximize available exemptions. It's a clean fit for many married couples in Cumming and Alpharetta who want to preserve flexibility without wasting exemption.
A QTIP trust makes sense when the surviving spouse needs support, but the family also wants to preserve principal for children from a prior marriage. That structure is often the right answer in blended families, especially when property division and inheritance goals don't line up neatly.
An irrevocable life insurance trust can remove life insurance proceeds from the taxable estate and create liquidity. That matters when heirs will need cash fast. A spousal lifetime access trust can be a smart middle ground when a spouse wants to remove assets from the estate but still keep practical access through the other spouse.
Practical rule: If the asset is likely to appreciate, move the appreciation out of the taxable estate sooner rather than later.
The tax angle is blunt. Transferring appreciating assets out of the taxable estate now can save a family 40 cents of estate tax on each dollar of future appreciation, using tools such as spousal lifetime access trusts, dynasty trusts, grantor retained annuity trusts, and intentionally defective grantor trust sales (Cerity Partners). That's why these structures belong in the conversation for families with meaningful real estate, business interests, or concentrated holdings.
If you're comparing a revocable trust to an irrevocable one, use the former for probate control and the latter for tax and asset-shifting advantages. The distinction matters, and a plain-language breakdown is available in this Miles Hansford trust comparison guide. Families in Johns Creek, Milton, and Roswell often need both clarity and control, not just one or the other.
Gifting Techniques to Reduce Your Taxable Estate
Gifting works because it moves future growth out of your estate while you're still alive to control the timing. This is the key advantage. It's not about being generous for its own sake; it's about using the rules to reduce what gets exposed later.
Make annual gifts with discipline
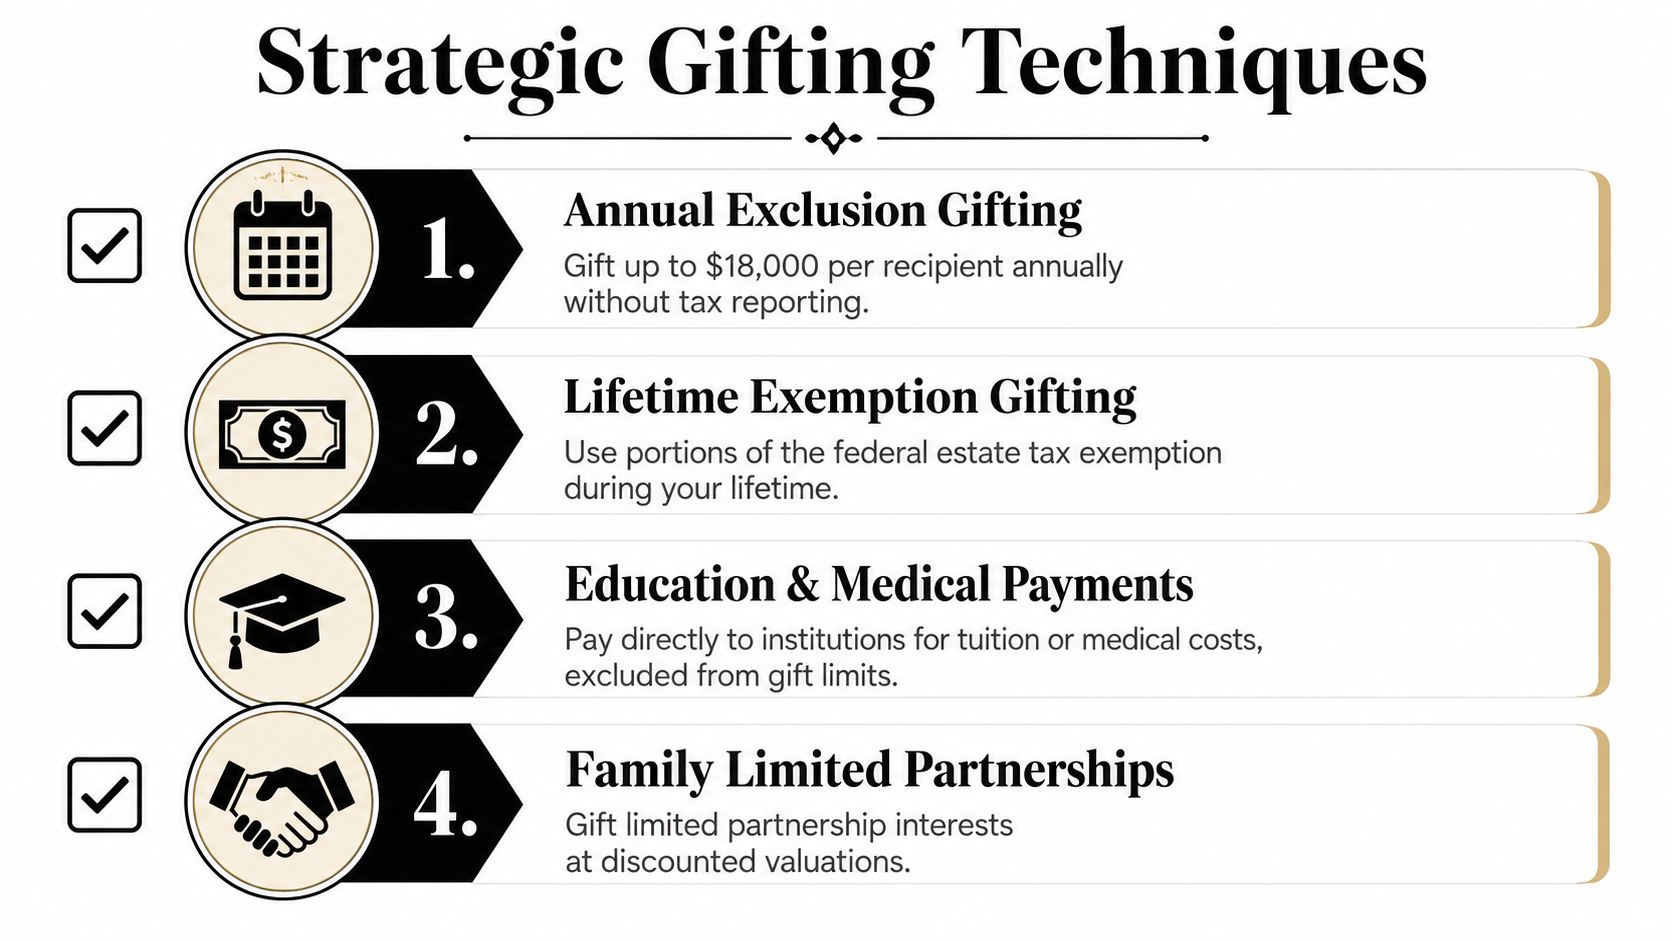
The annual exclusion is straightforward. In 2025 and 2026, you can give $19,000 per recipient each year without using lifetime exemption, and married couples can use gift-splitting to transfer $38,000 per recipient (Edward Jones). That's a quiet, repeatable tool, and it's especially useful for families in Cumming who want to help children, grandchildren, or trusts without triggering unnecessary tax exposure.
Don't make gifts casually. Document them, track the recipient, and coordinate them with your trust plan. If you're moving business interests or investment assets, timing and valuation matter more than people think.
Here are the gifting moves that usually deserve attention first:
- Annual exclusion gifts: Use them every year if your family can support the transfer.
- Lifetime exemption gifts: Use them when the asset is likely to appreciate and you want that future growth outside the estate.
- Direct tuition or medical payments: Pay the institution or provider directly when the structure fits your family's needs.
- Trust-based gifts: Move assets into the right trust if control, creditor protection, or multigenerational planning matters.
The annual exclusion only works well when the paperwork is clean. A sloppy gift can become an audit issue later, especially if the family business or real estate interest lacks a clear valuation trail. For local families in Forsyth County and Fulton County, that's not a detail, it's the difference between a clean transfer and a fight.
One practical outside resource on liquidity planning and insurance coordination is this guide to life insurance for Georgia families. Use that kind of tool when gifts are part of a larger plan, not as a standalone fix.
The Liquidity Problem Most Families Overlook
Most estate tax articles tell families to move assets out of the estate and call it a day. That advice is incomplete. If the heirs inherit a business, farm, or concentrated asset with no cash cushion, the tax bill can force a sale at exactly the wrong time.
Cash matters as much as tax minimization
The question is not only how much tax you save. It's how your heirs will pay the bill without being forced to unwind what the family built. That's especially true for owners in Forsyth County and Fulton County who hold operating businesses, real estate portfolios, or land that can't easily be divided.
That's why liquidity planning belongs at the center of the conversation. Life insurance, buy-sell agreements, and trust design can give heirs the cash they need without sacrificing control too early. They can also help avoid disputes among children who want different outcomes after a parent's death.
The contrarian point matters too. Sometimes retaining assets until death is rational because assets held until death generally receive a step-up in basis, which can reduce capital gains tax for heirs (Thrivent). For some families, that income-tax benefit can outweigh the estate-tax cost, especially when the asset has a very low basis and strong appreciation potential.
Don't treat estate tax as the only variable. The wrong transfer timing can create a bigger income-tax problem for your heirs.
If you're weighing insurance against outright gifting, the answer often depends on control. A family business owner in Alpharetta may prefer to keep voting control, preserve basis step-up on certain assets, and use insurance to create liquidity elsewhere. That's a very different plan from a retiree who mainly wants simplicity.
For families considering whether to keep or sell inherited land, a plain-English resource on disposition issues is this Georgia inherited property sale guide. It's useful because liquidity planning starts before the inheritance ever passes.
Business Succession and Valuation Planning
Business owners don't just need estate tax planning. They need a succession plan that holds up under pressure. If the business is the biggest asset in the estate, valuation and transfer structure become the whole game.
Valuation drives the tax result
The IRS cares about fair market value, but the family cares about continuity. That tension is why valuation discounts for lack of marketability and minority interests can matter. A properly structured transfer can move a larger slice of the economic value while using less exemption than a direct transfer of fully controlled ownership.
A buy-sell agreement helps set a predetermined value and a funding method if an owner dies, becomes disabled, or leaves. That's critical for businesses in Cumming and Alpharetta where family and nonfamily ownership can collide. If the agreement is weak or outdated, the estate may have theoretical influence but no practical path to a clean transition.
Family limited partnerships and LLCs can also support a controlled transfer. They let the senior generation keep management authority while gradually shifting noncontrolling interests to heirs. Used correctly, those entities can reduce exposure, support succession, and keep the business from becoming a courtroom fight.
If the documents don't match the real business relationship, the IRS and the family both see the weakness.
The documentation matters as much as the strategy. IRS scrutiny usually focuses on whether the valuation is defensible, whether the agreement was followed, and whether the transfer had a real business purpose. That's where a local planning team earns its keep.
For families building succession plans with legal oversight in North Georgia, this Miles Hansford business succession resource is a useful reference point. A good succession plan protects operations first, then cleans up the tax issue around it.
Common Pitfalls and Your Next Steps in Georgia
The biggest mistake I see is simple. Families wait until a crisis, then try to build a plan under pressure. That leads to missed elections, outdated beneficiary designations, and documents that no longer match the family's asset picture.
Don't let old documents run the family
If a spouse dies and the portability election is ignored, or if beneficiary designations still point to the wrong person, the family can lose planning opportunities that do not come back. If you make irrevocable gifts without planning for your own liquidity, you can create a personal cash problem while solving a tax problem for the next generation.
Estate tax planning is concentrated among a small share of decedents, so broad advice usually misses the point. Only about 0.25% of decedents had an estate tax return filed in 2022, and only about 0.14% paid estate tax. That is why the right plan has to be targeted, not generic.
Georgia families also need to keep local realities in view. There's no state estate tax in Georgia, but probate, trust funding, and court procedure still matter. If your family lives in Forsyth County, Fulton County, or nearby places like Suwanee, Dawsonville, Sandy Springs, or Canton, the practical details still affect how quickly your plan works. If heirs may need to sell inherited property to raise cash, the plan should also account for timing and liquidity, including a possible Georgia inherited property sale.
A clear next move
- Review the balance sheet. Know what is liquid, what is illiquid, and what is likely to appreciate.
- Check beneficiary designations. Retirement accounts and insurance often control more than the will does.
- Confirm trust funding. An unfunded trust is just paper.
- Coordinate with business documents. Buy-sell agreements and estate documents need to say the same thing.
- Update before the law shifts again. The current exemption window will not stay open forever.
For families in Cumming, GA and Alpharetta, GA, the right time to tighten this up is before a death, not after. Miles Hansford Law Firm works with Georgia families who need a calm, practical plan for estates, businesses, and inherited property, and that is the kind of review that can save your heirs from rushed decisions later.
If you are ready to protect your family's liquidity, preserve control of a business or family asset, and make sure your plan still works under Georgia law, schedule a consultation with Miles Hansford Law Firm. The attorneys at Miles Hansford Law Firm can review your exemption use, trust structure, and succession documents, then help you close the gaps before the planning window narrows further.