


If you're sitting in Alpharetta or Cumming trying to figure out whether a revocable living trust is worth the trouble, you're probably not thinking about abstract estate theory. You're thinking about a parent whose health is changing, a house in another state, a family business that can't sit idle, or the frustration of watching an estate get tied up in court. In North Georgia, those are the moments when people start asking a practical question, what does a revocable living trust solve, and what doesn't it solve?
A trust can be a smart tool, but it's not magic, and it's not for every family. For many people in Cumming, GA and Alpharetta, GA, the value is probate avoidance, privacy, and continuity, not tax elimination or asset shielding. If you want the straight answer before you sign anything, this guide lays it out the way I'd explain it across the desk in a local planning meeting, with the trade-offs included.
Why Alpharetta and Cumming Families Are Asking About Living Trusts
A lot of families start looking at revocable living trusts after a personal wake-up call. Maybe a parent in Milton needs help managing bills, or a couple in Johns Creek just inherited a cabin with property in another state and realizes the paperwork is more complicated than they expected. Sometimes the trigger is simpler, a friend in Roswell or Sandy Springs spent months, or longer, dealing with probate and the family decided they don't want that path for themselves.
That reaction makes sense. A revocable living trust is not a luxury document reserved for the ultra-wealthy, and it's not a substitute for every other estate planning tool. It's a way to organize property so it can move with less court involvement, more privacy, and better continuity if something happens to you.
The key is to keep expectations grounded. In Georgia, the trust only helps with assets that are titled into it, and the practical benefit is strongest when families own real estate, brokerage accounts, business interests, or property in more than one state. That is why people in Fulton County, Forsyth County, and the broader North Georgia corridor ask about it, they want a plan that fits the way they live, not a generic document that looks good on paper and fails in real life.
Practical rule: a trust is useful when it matches the asset list you already have, not the asset list you hope you'll eventually remember to transfer.
What a Revocable Living Trust Is
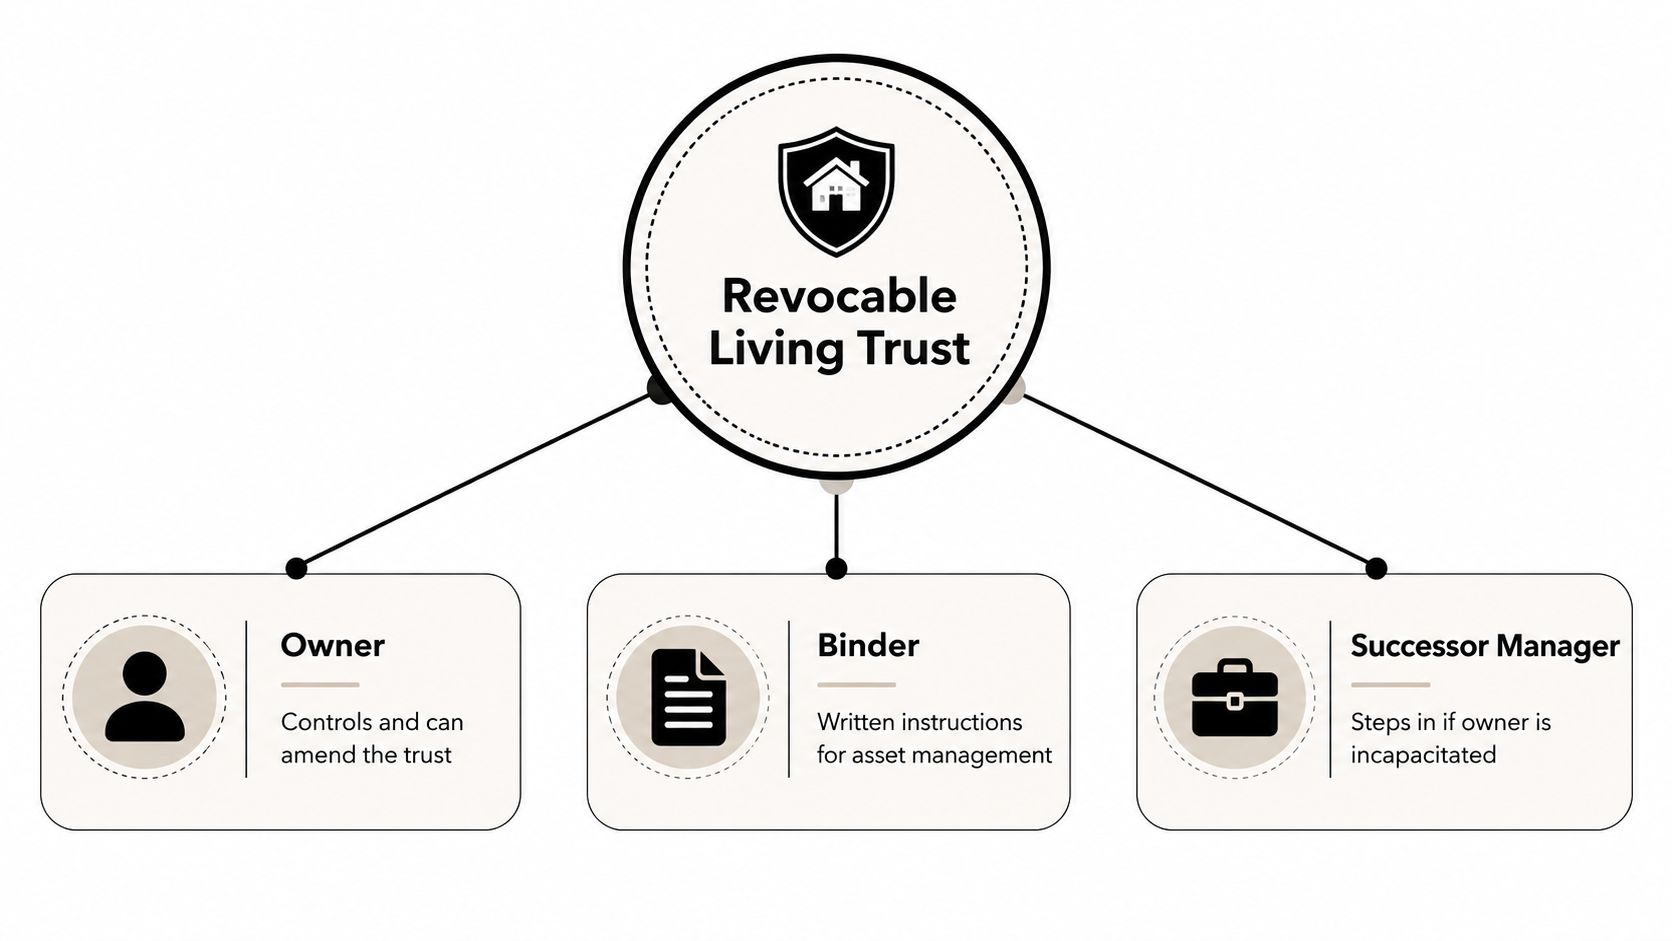
A revocable living trust is a written set of instructions that holds title to property while you are alive and competent, and those instructions can be changed or canceled during your lifetime. You place assets into the trust, name who will manage them, and spell out what happens if you become incapacitated or die. The structure has three roles, the grantor who creates it, the trustee who manages it, and the successor trustee who steps in later.
In day-to-day Georgia estate planning, the person who creates the trust usually keeps control and often serves as trustee during life. The Consumer Financial Protection Bureau guidance explains that a revocable living trust remains flexible while the grantor is alive, which is why it works as an administration tool rather than a fixed transfer of ownership Consumer Financial Protection Bureau guidance.
How Georgia treats the trust
Georgia recognizes the trust as a legal container, but the document does not create a tax shield by itself. During life, the trust is generally income-tax-transparent, so income is still reported on the grantor's return, and the grantor keeps the practical ability to use the property much as before revocable trust basics. That is why I describe it to clients in Forsyth County and Fulton County as a control-preserving document, not a separate entity standing apart from the family's finances.
The practical value is in management. Who pays the mortgage if you cannot, who handles the brokerage account, who keeps the property insured, and who follows your instructions without forcing the family into court first?
For a practical comparison of what changes, and what does not, a clear discussion of revocable trust vs will helps frame the choice before you decide which document belongs in your plan. If you want a Georgia-specific overview of the probate side of that decision, see how to avoid probate in Georgia.
How Probate Avoidance Works in Georgia
A revocable living trust gets attention for a simple reason. Families in Cumming and Alpharetta want to keep property out of the Georgia probate process when possible, and they want a plan that does not force everything through court after a death. In Georgia, probate is the court-supervised process for proving a will, appointing a representative, and giving that person authority to collect and distribute assets. In crowded dockets, especially in Forsyth County Superior Court and Fulton County Superior Court, that process can bring delay, extra filings, and a level of formality families do not want while they are already dealing with loss or disruption.
A properly funded trust changes the mechanics. Assets titled in the trust can be transferred by the successor trustee immediately on death, without waiting for a probate decree or letters testamentary. The trustee can handle liquidity, pay debts and expenses, and keep the estate moving while the court system deals with other matters.
Why this matters for North Georgia families
The benefit is strongest when the family owns property that cannot sit still. Real estate, marketable securities, and business interests often need prompt attention. If a brokerage account is already in the trust, it generally does not need to be re-registered after death, which helps preserve uninterrupted portfolio management during the transition Fiduciary Trust on revocable trust mechanics.
That same structure can also reduce ancillary probate, the extra court process triggered when someone owns real estate in another state. This comes up often for North Georgia families with ties to Florida, the Carolinas, or the coast, especially when they own a second home or rental property outside Georgia. For a Georgia-specific overview of the probate side of that issue, see how probate avoidance works in Georgia. Maryland's estate-planning guidance notes that a revocable trust can help minimize or avoid probate for transferred assets and can also help minimize or avoid ancillary probate when property sits in more than one state Maryland Register of Wills guidance.
The trust only works on the assets that are inside it. If a house, account, or business interest never gets retitled, that asset can still end up in probate.
That is the detail people miss. Probate avoidance is real, but it is not automatic. It depends on funding the trust correctly, and that is where many plans succeed or fail.
For families comparing how much planning they want around future care, even traditional versus hybrid care policies can affect whether a trust is the right piece of the larger plan. A revocable trust can help organize the transfer of assets, but it does not replace the need to make the assets part of the trust in the first place.
Privacy, Incapacity Planning, and Retained Control
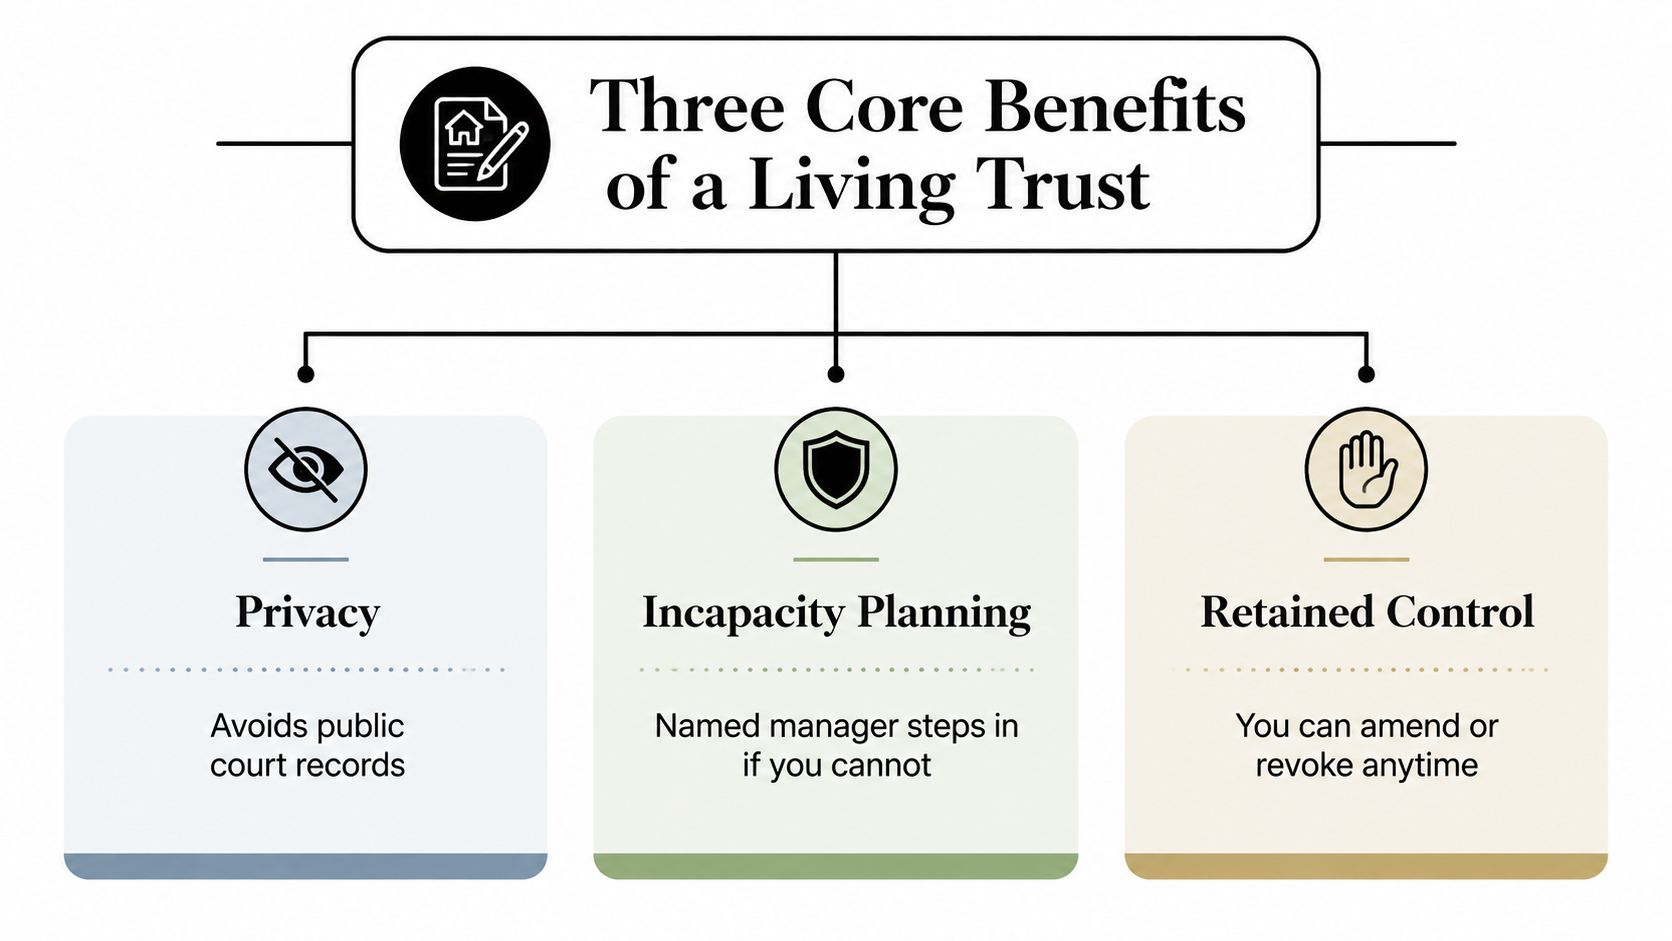
For a lot of families, the practical value is not the headline benefit. It is the way a revocable living trust keeps the family out of unnecessary court supervision when life gets messy. Probate records in Georgia are public, while trust administration usually stays private, so the trust gives families a more discreet way to transfer assets and handle routine administration.
That privacy is limited. Some transfers or related legal steps can still surface through other court or administrative records, so clients should expect better privacy, not perfect secrecy. A Georgia probate file is still part of the public record, and a trust does not erase every paper trail that comes with ownership changes or later administration.
Incapacity planning is where the trust earns its keep
If a Cumming business owner suffers a stroke, or an Alpharetta parent develops dementia, the successor trustee can step in under the trust's terms without waiting for a guardianship or conservatorship proceeding. That continuity matters because bills still have to be paid, investments still have to be monitored, and property still has to be maintained. The trust gives your chosen person authority to act under your instructions rather than asking a court to build a plan from scratch revocable trust administrative benefits.
In Georgia, that kind of continuity can spare a family a court proceeding at the very moment it is already dealing with a medical crisis. Forsyth County and Fulton County courts handle incapacity matters through formal filings, notices, and judicial oversight, which is exactly what many families want to avoid when the trust already names a capable successor. The trust does not replace every legal document a family may need, but it does keep day-to-day management from stalling.
Retained control is the trade-off people like most
You do not give up practical control. While you are mentally competent, you can amend or revoke the trust, keep using the assets, and change the plan as family circumstances change. That flexibility is why many people in North Fulton and Forsyth County prefer a living trust over a rigid arrangement that locks them into choices they may later need to change.
Families comparing long-term care approaches often look at traditional versus hybrid care policies at the same time they are considering a trust. That comparison makes sense. A revocable trust can organize who manages assets and how they pass, but it does not pay care costs or replace a separate plan for long-term care risk.
What a Revocable Living Trust Does Not Do
A revocable living trust does not reduce your income tax while you are alive. For tax purposes, the grantor is still treated as the owner, so the trust's income is reported on the grantor's return, and the assets are generally still included in the grantor's taxable estate as noted earlier. That is the first trade-off clients need to understand in an Alpharetta or Cumming estate plan.
People often hear the word “trust” and assume it solves every money problem. It does not. A revocable trust is a control and administration tool, not a tax shelter and not a blanket protection device.
It usually does not shield property from claims
Because the grantor keeps the power to amend or revoke the trust, those assets are generally not insulated from creditors, divorcing spouses, or the financial consequences tied to ownership. They are also typically part of Medicaid eligibility review in many situations, which is why a revocable trust is not the right answer if the goal is long-term care asset protection. Consumer Financial Protection Bureau explanation explains the basic structure, and the practical point is simple, control is the reason the trust works, and control is also the reason it usually does not protect the property from claims.
That matters in Alpharetta, Roswell, and Sandy Springs, where families sometimes want one document to handle privacy, inheritance, divorce, and care-cost concerns all at once. A revocable trust does a good job with administration and continuity. It does not create the kind of barrier people usually mean when they ask about asset protection.
What the tax side really means
A revocable trust also does not remove the estate-tax question by itself. The trust remains part of the owner's estate for tax purposes while it is revocable, so families who are trying to reduce transfer taxes need to look at a different structure or a more deliberate combination of documents. For a plain-English comparison of those trade-offs, see this revocable trust vs. irrevocable trust guide.
That is where candid planning matters. In Georgia, a revocable trust should be used for what it does well, private administration, continuity if you become incapacitated, and keeping the plan flexible while you are alive. It should not be sold as a cure-all for taxes, creditors, or every risk that comes with property ownership.
What to expect instead
If you are trying to protect assets from a pending divorce, creditor exposure, or long-term care costs, you may need another tool, or a combination of tools, depending on your timing and goals. A revocable trust can fit into that plan, but it does not replace the separate planning that those risks require.
That is the honest part of the conversation. A good Georgia trust plan should say clearly what the document does, what it leaves untouched, and whether a revocable trust is the right fit for your family.
Revocable Trust vs Will vs Irrevocable Trust
A lot of Alpharetta and Cumming families are not really choosing between a will and a trust. They are choosing among three tools that solve different problems. A will still matters for certain decisions, especially naming guardians for minor children. A revocable living trust gives you a flexible way to hold and administer assets. An irrevocable trust serves a different purpose, usually tied to stronger transfer planning, tax planning, or protection goals.
| Estate Planning Tools Compared for Georgia Families | Will | Revocable Living Trust | Irrevocable Trust |
|---|---|---|---|
| Probate avoidance | Usually no | Yes, for funded assets | Often yes, depending on structure |
| Privacy | Limited, probate is public | Stronger privacy during administration | Often stronger privacy |
| Control during life | Full control | Full control, with flexibility to amend or revoke | Reduced control |
| Tax treatment | No built-in tax change | Income-tax-transparent during life | Can have different tax effects depending on design |
| Creditor protection | Limited | Limited | Often stronger, depending on terms |
| Best fit | Basic transfer, guardianship nominations | Probate avoidance, continuity, privacy | Asset protection or tax strategy |
How the decision usually works in Georgia
If your main concern is naming guardians and leaving a simple transfer plan, a will may still be the right tool. If your main concern is keeping assets out of probate and giving someone a clear path to manage things during incapacity, a revocable trust usually fits better. In Georgia probate courts, especially in Forsyth County and Fulton County, the difference shows up in how quickly assets can be accessed, how public the process becomes, and how much paperwork the family has to carry through the court process.
An irrevocable trust belongs in a different conversation. Families use it when they want to move assets out of the taxable estate, build stronger protection against certain claims, or set rules they are willing to live with even if circumstances change. That trade-off matters. Once control is reduced, so is flexibility, and that is a real cost, not just a technical one. For a plain-English comparison of those differences, see this revocable trust versus irrevocable trust discussion.
Bottom line: many families do not choose between a will and a trust. They use a revocable trust with a pour-over will, a healthcare directive, and a financial power of attorney so the whole plan works together.
The honest answer in Georgia is that each document has a job. A will handles guardianship and anything left outside the trust. A revocable trust handles funded assets with more privacy and continuity. An irrevocable trust is the tool people use when they want different tax results or a stronger barrier, and they are willing to give up control to get it.
How to Implement a Revocable Living Trust in Georgia
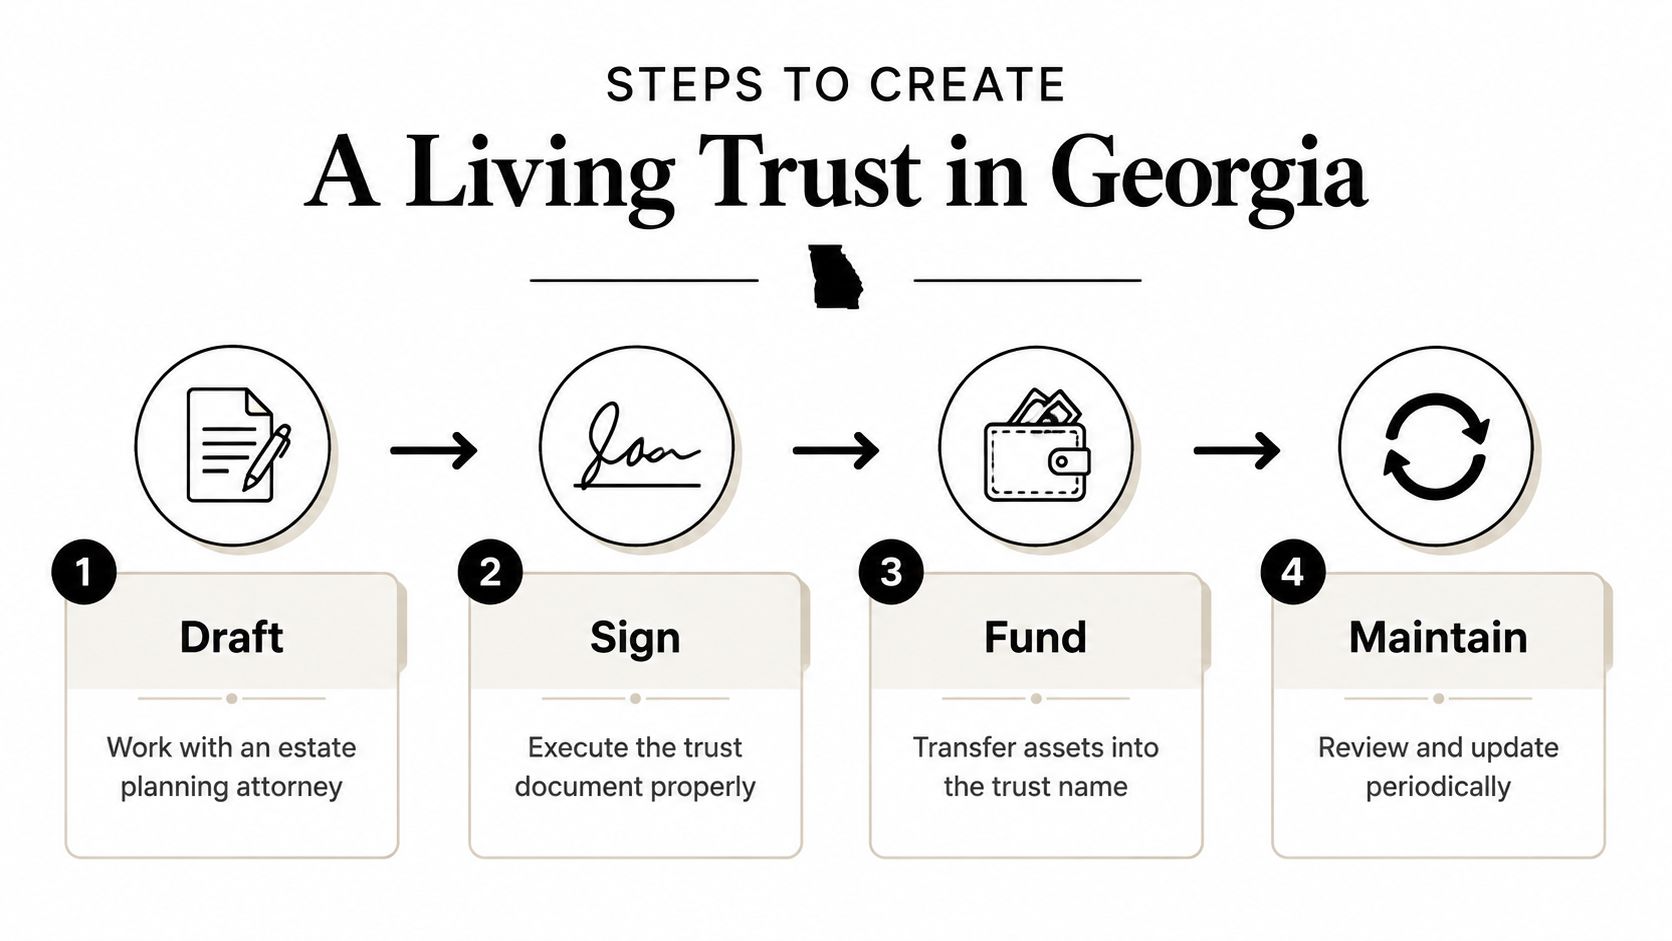
A trust that sits in a drawer doesn't help much. The work starts with drafting, but it ends with funding and maintenance. In practice, that means sitting down with a Georgia estate planning attorney, signing the trust correctly, and then retitling the right assets into the trust so the probate-avoidance benefit exists.
The steps that matter most
Start with the trust document itself, then transfer deeds, brokerage accounts, and business interests into the trust name. Review beneficiary designations on retirement accounts and life insurance so they don't conflict with the plan. If you buy a new house in Alpharetta, open a new brokerage account, or inherit property in Cumming, those assets need to be checked again.
Common mistakes are easy to make and hard to spot:
- Leaving new property outside the trust: a recently purchased house can still end up in probate if the deed never gets updated.
- Forgetting an old brokerage account: a forgotten account in your personal name can defeat the clean transition you expected.
- Naming the trust where the institution won't accept it: retirement accounts require careful coordination, because the beneficiary form has to work with the custodian's rules.
- Never reviewing after major life events: marriage, divorce, birth, death, and relocation all call for a fresh look.
A good successor trustee should be organized, calm, and willing to follow instructions, not just willing to say yes. Keep a trust binder with the signed trust, deeds, account information, and contact details for advisors so the person stepping in can do the job.
For families who want a practical roadmap, how to establish a revocable living trust is the right process question to ask before funding begins.
Next Steps for Your Alpharetta or Cumming Family
Start with a list of what you own, what already has beneficiary designations, and what sits in your individual name. If you own property in more than one state, or you want someone to manage finances without court involvement if you become incapacitated, bring that up directly in the consultation. Those facts drive the plan more than general rules do.
Miles Hansford Law Firm works with families across Alpharetta, Cumming, Forsyth County, Fulton County, Johns Creek, Milton, Roswell, and the broader North Georgia region on practical estate planning questions like these. If you want a confidential, pressure-free conversation about whether a revocable living trust fits your family, schedule a consultation and come ready with your current documents.
Miles Hansford Law Firm helps North Georgia families evaluate revocable living trust benefits, probate concerns, and the documents that need to work together in real life. If you're ready to talk through your options with a local team that handles estate planning and related family matters every day, visit Miles Hansford Law Firm and schedule a consultation.