


If your family is in Cumming or Alpharetta and someone just told you, “the brokerage account has a transfer on death form,” don't assume the money will be available right away. I've seen grieving families expect a smooth handoff, then run into paperwork, beneficiary questions, and delays while everyone is already stretched thin. That's the part most guides skip, and it's where families in Forsyth County and Fulton County can get hurt if nobody is paying attention.
Transfer on death accounts are powerful, but they're not magic. They can keep assets out of probate, yet they still require the right paperwork, the right beneficiary language, and the right follow-through after death. If you live in North Georgia and you want to protect your family, your ex-spouse, your children, and your estate plan from avoidable mistakes, you need to understand how these accounts work.
Why Transfer on Death Accounts Matter for Georgia Families
A family in Alpharetta can do everything right on paper and still get stuck after the funeral. The account owner dies, the brokerage account is supposed to pass to the named beneficiary, and then the surviving family finds out the institution still wants a death certificate, distribution forms, and sometimes additional paperwork before the money moves. That is the burden with a TOD account. Probate may be avoided, but administration does not disappear.
For families in Cumming, Johns Creek, Milton, Roswell, Suwanee, and Dawsonville, that matters because estate planning is never just about signing documents. It is about getting money to the right person without triggering conflict, delay, or a fight over what the owner meant. In Georgia, that pressure gets worse when divorce, child custody, alimony, and property division are already part of the family picture.
A transfer on death account is a beneficiary arrangement with a financial institution. The account passes by contract, not by will, and the beneficiary form controls who receives the asset at death. FINRA explains that brokerage firms use TOD paperwork for these accounts, and the assets transfer after the owner dies once the required proof is provided, outside probate and directly to the named beneficiary (FINRA on brokerage account assets at death). That makes TOD designations useful, but also easy to misuse.
Practical rule: A TOD form is only as good as the beneficiary list on it. If the form is outdated, incomplete, or inconsistent with the family situation, the account can still create trouble.
Georgia divorce law makes account titling more than paperwork. After a divorce, assets can be caught between an old beneficiary designation and a new family reality, which is why families should review all account designations alongside broader planning and probate-avoidance strategies in Georgia.
The point is simple. If you are trying to protect your family in Forsyth County or Fulton County, treat a TOD account as one tool in the plan, not a shortcut that solves everything on its own. That is especially true if you are facing divorce, remarriage, or a blended family situation in North Georgia.
How Transfer on Death Accounts Work Under Georgia Law
A transfer on death account is a contractual beneficiary designation, not a will. The financial institution controls the account agreement, and the beneficiary form controls who gets the asset at death, even if a will says something different. That is the first thing Georgia families need to understand, because the paperwork on file usually decides the result.
The account owner keeps control during life. The owner can buy, sell, withdraw, or retitle the account if the institution allows it, and the beneficiary has no ownership rights until death. After death, the beneficiary still has to give the institution the documents it requires before the transfer is completed. That is why these accounts avoid probate, but they do not avoid administration.
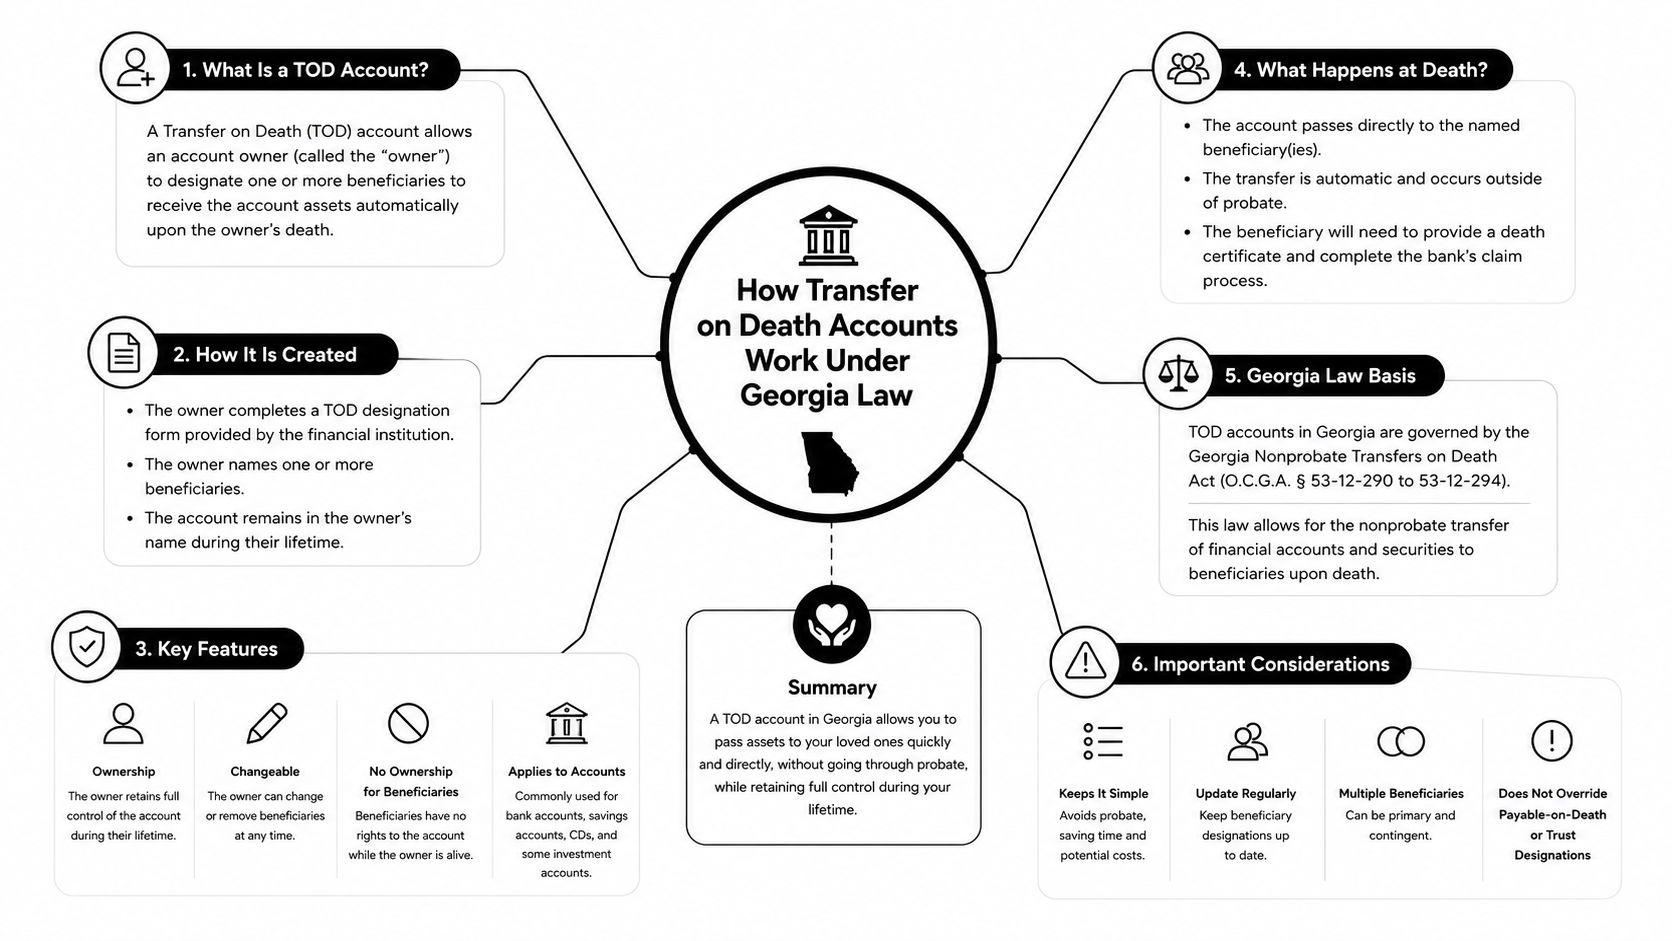
The practical problem shows up after the account owner dies. The beneficiary may need a death certificate, a claim form, identity verification, and a tax form before the financial institution releases the asset. If there are multiple beneficiaries, a minor beneficiary, or a beneficiary who cannot be located quickly, the account can sit idle while the family gathers what the institution demands. Families in Alpharetta and Cumming often expect a direct transfer to mean immediate access, but the paperwork still has to be handled correctly.
Georgia divorce law makes account titling more than paperwork. In a divorce, assets can be subject to equitable division, so the way an account is titled can affect negotiations, temporary orders, and final property division. A TOD form does not erase divorce issues, and it does not make an account invisible just because it has a beneficiary attached. If you are in the middle of a Fulton County or Forsyth County divorce, beneficiary planning and property division need to be coordinated, not handled as separate afterthoughts.
Bottom line: TOD avoids probate, not estate-tax exposure. Inherited TOD assets generally receive a step-up in basis under Internal Revenue Code Section 1014, and the account value is still included in the decedent's gross estate for federal estate-tax purposes, as explained in LegalClarity on TOD administration and tax treatment.
For Georgia families, that means a TOD account can be efficient, but it is not a full estate plan. It still has to fit with the rest of the picture, including account titling, beneficiary review, and the broader choice of how to avoid probate in Georgia. If a family is also dealing with real estate that must be sold after death, the account transfer often has to be coordinated with Property Nation probate solutions.
Comparing TOD Accounts to POD, Joint Ownership, and Trusts
Not every nonprobate tool does the same job. People often hear “avoid probate” and assume every shortcut is equally good. That's wrong. A transfer on death account, a payable-on-death bank designation, joint ownership, and a revocable trust all work differently, and the right choice depends on who you're trying to protect.
A TOD account is usually clean for brokerage assets. A POD designation works similarly for bank accounts. Joint ownership can look simple, but it can create unintended consequences in a Georgia divorce, especially in high-asset cases in Alpharetta and Cumming. A revocable trust gives more control for blended families, minor children, or families that need a coordinated plan across multiple assets in Forsyth County and Fulton County.
| Estate Transfer Tools Compared for Georgia Families | TOD Account | POD Designation | Joint Ownership | Revocable Trust |
|---|---|---|---|---|
| Control during life | Owner keeps control | Owner keeps control | Shared control with another owner | Trustee follows trust terms |
| Probate avoidance | Yes | Yes | Usually yes at death of joint owner | Yes |
| Creditor exposure | Asset remains part of owner's estate during life | Asset remains part of owner's estate during life | Can create ownership exposure during life | Depends on trust structure and asset handling |
| Divorce risk | Can be changed, but needs review after filing | Can be changed, but needs review after filing | Can create serious divorce complications | More flexible for coordinated planning |
| Tax treatment | Step-up in basis may apply at death, estate inclusion still applies | Similar practical treatment for bank funds | Depends on ownership structure | Depends on trust and asset type |
| Minor beneficiaries | Poor fit without extra planning | Poor fit without extra planning | Poor fit | Better fit with instructions and trustee control |
The strongest argument for a trust is flexibility. If you have minor children, a second marriage, or unequal inheritance goals, a trust can handle contingencies that a simple beneficiary form cannot. That is why people with more complicated family structures should not default to the easiest option just because it looks tidy.
If you're also dealing with property that may need to be sold during probate, a resource like Property Nation probate solutions can help families understand the practical side of real estate administration. For legal planning, though, the better move is to coordinate the account titles with the rest of the estate documents so the left hand and right hand are working together.
For a fuller comparison of trust planning, see what a living trust does for your assets.
Step-by-Step Setup Checklist and Beneficiary Language
A TOD account should be set up deliberately, not casually. Brokerage firms and banks usually have their own beneficiary forms, and you need the right one for the specific account type. If you skip the details, you can create a result that looks fine today and fails the family later.
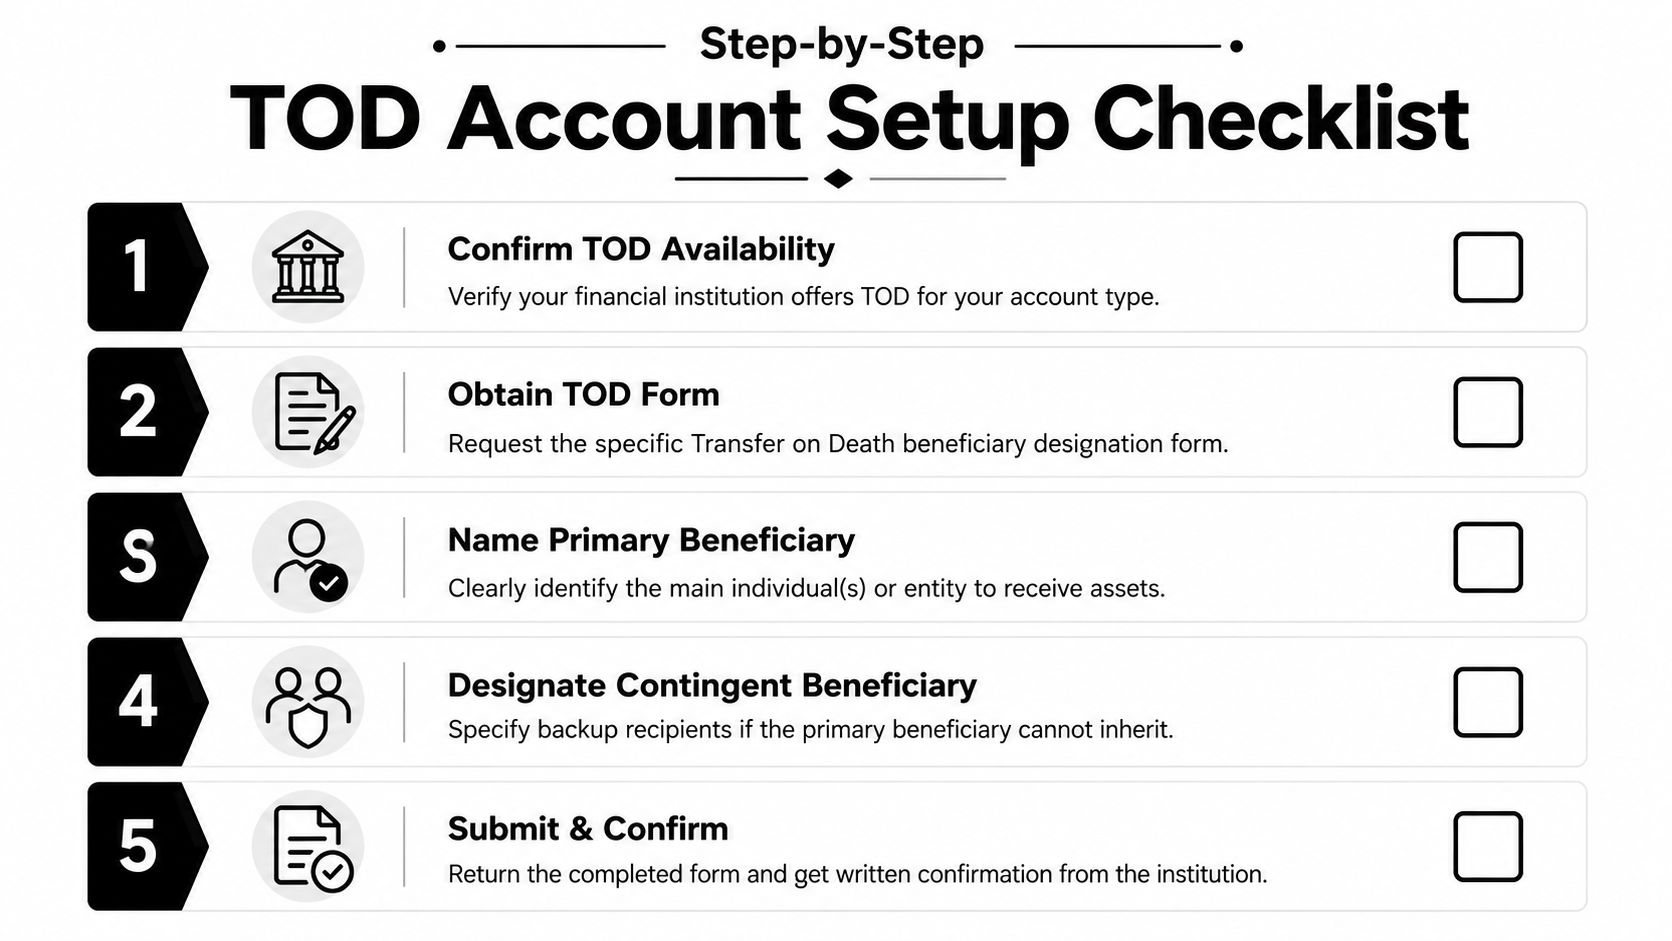
The setup checklist that actually matters
Confirm TOD availability. Not every account type uses the same form, so the institution has to confirm the account can carry a transfer on death designation.
Name primary and contingent beneficiaries. If the first person dies before you do, the form should say who takes next.
Decide how shares pass. If you want children to share equally, the form should say so clearly. If you want a different split, write it down before the form is signed.
Coordinate with your will and other beneficiary forms. The TOD form controls that account, so it should match the rest of your estate plan.
Review after major life events. Divorce, remarriage, and the birth of a child are the big triggers. If you're in Roswell, Suwanee, or North Atlanta, do not leave old beneficiary designations in place and hope everyone “understands.”
A cleaner beneficiary clause might read, “Primary beneficiary, my spouse, if living, otherwise my children in equal shares, per stirpes.” That kind of language matters because it tells the institution what to do if someone predeceases you. The ACTEC guidance notes that beneficiary forms are often simple and may not explain what happens in that situation, which is exactly where avoidable disputes begin (ACTEC).
A beneficiary form that is “simple” for the bank can be dangerously vague for your family.
If the form allows only plain names and percentages, be precise. If your family has stepchildren, a disabled child, or a prior marriage in the background, do not guess. Get the language aligned with the estate plan before you sign.
The Post-Death Administration Reality Most Guides Ignore
A TOD account does not move money by itself the day the owner dies. Families learn that fast. The account avoids probate, but the beneficiary still has to push the transfer through the institution's own process, and that process takes paperwork.
Banks and brokerages usually want a death certificate, an affidavit of domicile, and a distribution request before they release anything. Some institutions also require the beneficiary to open a receiving account first. In many cases, the transfer is made in kind, so the beneficiary receives securities rather than cash right away, which can matter if the family expected immediate liquidity (Wells Fargo Advisors transfer on death designations report).
When there are several TOD accounts at different firms, the work multiplies. One company may want one form, another may insist on a different affidavit, and the beneficiary may be sitting in another state trying to gather signatures, copies, and account details. Families lose time there because they assume probate avoidance means no administration at all. It does not.
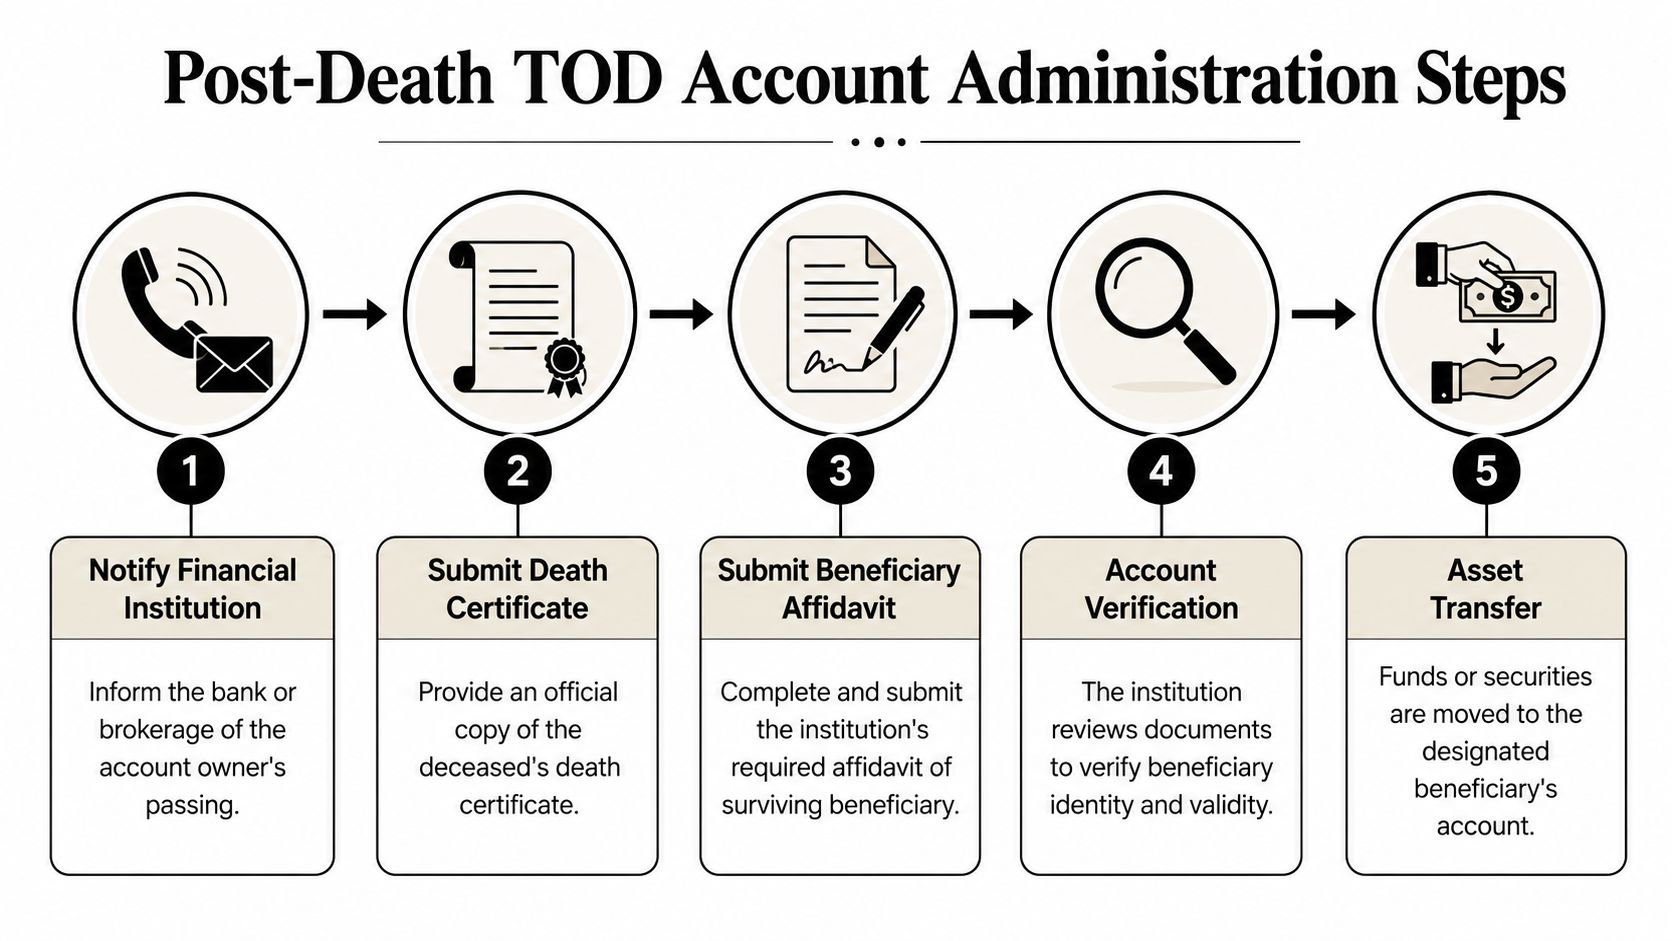
The usual sequence is straightforward, but it still takes follow-through. Notify the institution. Submit the death certificate. Complete the beneficiary paperwork. Wait for verification. Then receive the transfer. The broader process of handling a decedent's property follows the same kind of ordered steps described in the steps of estate administration, and that is exactly why these transfers still need organization.
If the beneficiary is grieving, out of state, or unfamiliar with financial forms, even a simple TOD transfer can stall. That is the hidden cost people miss. Probate avoidance is useful, but it does not eliminate the administrative burden on the family, and in North Georgia that burden often lands on people who are already trying to manage court notices, household accounts, and other estate tasks at the same time.
When to Consult a North Georgia Estate or Family Law Attorney
You should get legal help before you rely on a TOD form if your family is even slightly complicated. That includes blended families, minor beneficiaries, business ownership, or any case where a divorce is underway or likely. Once a beneficiary designation is signed and left untouched, it can override what you thought your will would do.
Georgia no-fault divorce, the 30-day minimum waiting period, temporary hearings, parenting plans, and equitable division all affect how I look at account titling. In Forsyth County Superior Court and Fulton County Superior Court, those issues do not stay neatly separated. If you are in a custody dispute, a high-asset divorce in Alpharetta, or a property division fight in Cumming, you need every asset designation lined up with the rest of the case strategy.
Red flags that call for lawyer review
Blended family terms: Old beneficiary forms can disinherit a current spouse or leave children from a prior marriage in conflict.
Minor children: TOD accounts do not solve guardianship, trustee control, or age-of-distribution issues by themselves.
Divorce filings: A TOD form signed before or during divorce can create a fight if nobody updates it.
Business or investment complexity: Multiple accounts, different institutions, and separate titling choices can pull against each other.
Contested estate planning: If siblings, stepchildren, or second spouses are involved, the form language needs to be deliberate.
For families in Johns Creek, Milton, Dawsonville, and Sandy Springs, the safest approach is simple. Review the TOD designation, then review the will, trust, and any divorce-related orders together. If those documents do not match, fix them before someone dies or the account owner signs a settlement agreement.
Miles Hansford Law Firm handles family law, divorce, custody, legitimation, modifications, contempt actions, property division, and estate-related planning issues in North Georgia. If you need a coordinated strategy that respects both your family law case and your estate plan, schedule a consultation before making a beneficiary change you can't easily undo.
Frequently Asked Questions for Alpharetta and Cumming Residents
Q: Do transfer on death accounts protect assets from divorce in Georgia?
A: No. A TOD form does not shield an asset from divorce issues in Georgia. If the account is part of the marital picture, equitable division still matters in Forsyth County or Fulton County, and a pending divorce can make an outdated designation a serious problem.
Q: How do TOD accounts affect child support or parenting plans?
A: They usually do not replace child support or parenting plan obligations. Georgia courts still control custody, support, and parenting issues, and a TOD beneficiary form does not change those orders. If the account owner dies, the beneficiary transfer happens separately from those family-law duties.
Q: What happens if my TOD beneficiary dies before I do?
A: The answer depends on the form. If you named a contingent beneficiary, that person may take the account. If you didn't, the result can get messy fast, which is why beneficiary language should be reviewed after divorce, remarriage, or a new child.
Q: Are TOD accounts included in the gross estate for federal estate-tax purposes?
A: Yes. TOD transfers avoid probate, but the account value is still included in the decedent's gross estate for federal estate-tax purposes. The transfer may still receive a step-up in basis at death, but that does not remove estate-tax exposure.
Q: Can I use a TOD account instead of a will in Georgia?
A: No. A TOD account only controls that specific asset. You still need a will for everything that doesn't pass by beneficiary form, and Georgia families in Cumming and Alpharetta should keep the two documents aligned.
Q: Do courts in Forsyth County or Fulton County care about beneficiary forms during divorce?
A: Yes, indirectly. The courts care about property division, temporary orders, and final agreements, and beneficiary forms can affect how assets are treated if someone dies or changes a designation during the case. Don't treat the form as separate from the divorce strategy.
Miles Hansford Law Firm helps North Georgia families protect assets, align beneficiary designations with divorce strategy, and avoid the mistakes that turn simple planning into expensive conflict. If you're dealing with a TOD account, a divorce, or a larger estate plan in Cumming or Alpharetta, visit Miles Hansford Law Firm and schedule a consultation before you sign the wrong form or leave the wrong beneficiary in place.